Does frequent crypto trading automatically make you a “trader” for U.S. federal tax purposes? No. Trading frequency gives you activity to document and review, but it doesn’t settle your tax classification. Understanding crypto tax for traders starts with separating the transactions you can substantiate from any tax status you may or may not qualify for.
If you trade across exchanges, personal wallets, and on-chain platforms, reconciling the details can take time. It may also be difficult to tell a taxable sale or exchange from a transfer between wallets you control. Keeping records that connect activity across accounts helps you review what happened and spot information that’s missing.
This guide explains the scope and limits of general U.S. federal tax guidance for active crypto trading in 2026. You’ll learn which activity may need reporting, what information to preserve, and why the label “trader” doesn’t automatically determine how the IRS treats your activity.
We’ll also cover when a crypto tax professional may help, particularly if your records span multiple platforms or include complex on-chain transactions. The goal is to build a complete, traceable picture of your activity and know when to check current IRS guidance or seek specialist support.
Key Takeaways
- Understand what U.S. federal guidance covers and why tax analysis depends on transaction facts, not simply the label you use.
- Learn how proceeds, cost basis, and realized gain or loss help describe trading activity for tax reporting.
- Use a structured recordkeeping workflow to gather statements, transaction details, timestamps, and available fee records.
- See why crypto tax for traders requires distinguishing trading activity from any separate tax classification or election.
- Prepare a clear record set and list of unresolved questions before seeking specialist crypto tax filing support.
Crypto tax for traders: what U.S. federal tax guidance covers
This section focuses on U.S. federal income tax considerations for people trading digital assets. It offers practical context for organizing activity, not personalized tax advice. The right analysis depends on what happened in each transaction and the rules that apply to it.
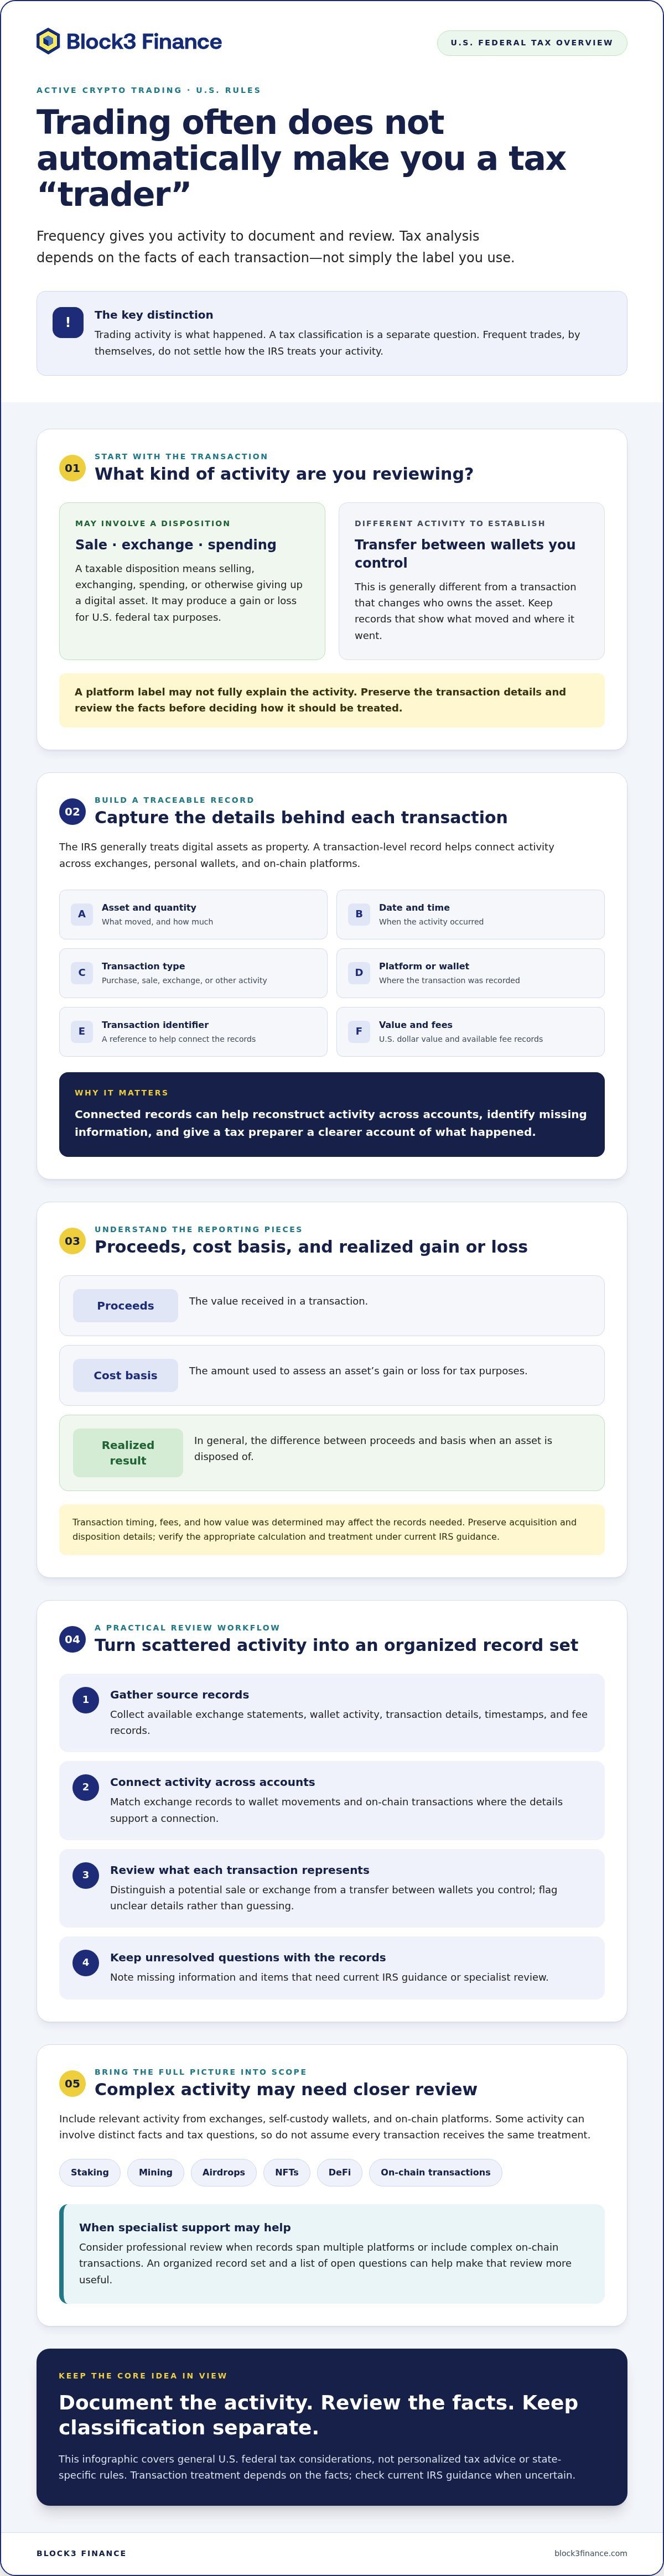
The phrase “crypto tax for traders” describes reporting questions that can arise when you buy, sell, exchange, or use digital assets. It doesn’t establish a special tax status. Calling yourself a trader, or making frequent trades, doesn’t by itself determine how the IRS treats your activity.
For U.S. federal tax purposes, the IRS generally treats digital assets as property. A sale or exchange may therefore require a different analysis from a transfer between wallets you own. To learn about crypto tax filing and reporting, consider how complete records can support tax preparation.
A taxable disposition is a transaction in which you sell, exchange, spend, or otherwise give up a digital asset, an event that may produce a gain or loss for U.S. federal tax purposes. Whether a specific transaction has a tax consequence depends on its facts. Check current IRS guidance if you’re uncertain about how an activity should be treated.
What does crypto tax for traders mean under U.S. rules?
It means reviewing the tax reporting questions connected to trading activity under U.S. federal rules. That activity may involve multiple assets, centralized exchanges, self-custody wallets, and on-chain transactions. To build a complete picture, you may need to reconcile records from more than one source.
This section covers U.S. federal considerations only. It isn’t a substitute for advice based on your circumstances, and it doesn’t address state-specific tax rules.
Which trading activity should readers bring into scope?
Start with purchases, sales, exchanges, and relevant on-chain activity. A transfer between wallets you control is generally different from a transaction that changes who owns the asset, but you’ll need records to establish what happened. Preserve transaction details rather than assuming a platform label fully explains the activity.
Staking, mining, airdrops, NFTs, and decentralized finance (DeFi) can involve distinct facts and tax questions. Include them in your review, but don’t assume every transaction in these categories receives the same treatment. When details are unclear, keep the supporting records and confirm the current U.S. federal treatment with the IRS or a qualified tax professional.
How crypto trading activity becomes tax-reporting information
For U.S. federal tax preparation, a transaction needs enough detail to show what moved, when it moved, and what value was involved. The IRS treats digital assets as property, and its U.S. federal tax guidance is a starting point for understanding reporting responsibilities. The treatment of an individual transaction still depends on its facts.
Build a transaction-level record rather than relying on a year-end account balance. Where available, save the asset and quantity, date and time, transaction type, platform or wallet, transaction identifier, U.S. dollar value, and related fees. These details can help connect an exchange record to an on-chain movement and show where information needs review.
Consistent transaction-level records give a tax preparer a traceable account of what happened, making it easier to evaluate each transaction under applicable U.S. federal rules.
How do proceeds and cost basis fit together?
Proceeds are the value received in a transaction. Cost basis is the amount used to assess an asset’s gain or loss for tax purposes. In general, a realized gain or loss is the difference between proceeds and basis when an asset is disposed of. Check current IRS guidance for the precise calculation and treatment.
Fees, transaction timing, and how an asset’s value was determined may affect the records needed for analysis. Don’t assume one cost-basis method applies to every situation. Preserve acquisition and disposition details so the appropriate approach can be verified for your circumstances.
Hypothetical example: A trader acquires a digital asset on one platform, later exchanges it for a different asset through a wallet, and pays a network fee. The acquisition record, exchange details, fee information, timestamps, and transaction identifier can help a preparer reconstruct the activity. This example illustrates recordkeeping only; it doesn’t determine tax treatment or predict anyone’s tax liability.
Why can exchange and blockchain records tell different parts of the story?
An exchange export may show trades completed on that platform but omit activity through another wallet or service. Blockchain records can help document transfers and transactions, but a transaction hash alone doesn’t establish the full tax context, such as who controlled the wallet or why the assets moved.
Where available, compare timestamps, asset quantities, transaction identifiers, and wallet ownership across records. If activity spans several platforms or the records don’t reconcile, a crypto tax professional can help review the information. You can discuss crypto tax reporting support with Block3 Finance.
Does frequent crypto trading automatically make you a tax trader?
No. Frequent crypto trading alone doesn’t automatically establish a special tax status under U.S. federal rules. “Trader” may simply describe someone who trades often. A tax classification is a separate question that depends on the applicable rules and the facts of the person’s activity.
This distinction matters because crypto tax for traders isn’t determined by trade count alone. A high volume of transactions can make thorough records especially important, but it doesn’t guarantee a particular classification or tax outcome. For broader background on crypto trading activity and related reporting considerations, see Bloomberg Tax, and confirm specific U.S. federal treatment with current IRS guidance and a qualified tax professional.
How is trading activity different from tax classification?
Activity level is one fact to review, not a conclusion by itself. A professional may need to consider the purpose and consistency of the activity, the records available, and the taxpayer’s circumstances under relevant U.S. federal rules.
Keep evidence that helps explain your activity, such as transaction histories, account records, and how you tracked trading decisions. Don’t rely on a label you use for yourself or assume that one pattern of activity automatically qualifies. Any classification should be assessed against current authoritative guidance and your full facts.
What should traders know about a possible mark-to-market election?
Section 475(f) of the U.S. Internal Revenue Code is associated with a mark-to-market election in certain trader tax contexts. Mark-to-market generally refers to valuing assets at market value for tax purposes, but that brief description doesn’t establish whether the provision applies to a particular crypto trader or asset.
Treat Section 475(f) as a specialist-review question, not a default treatment. Don’t assume eligibility, timing, procedure, or tax consequences based on general online summaries. The election’s relevance depends on the taxpayer’s facts and applicable U.S. rules, so confirm current requirements with the IRS and a qualified tax professional before acting.
A practical workflow for organizing crypto trader tax records
For U.S. federal tax preparation, the goal is to turn activity across platforms and wallets into a traceable transaction history. Follow a consistent workflow, preserve original files, and record unresolved questions rather than filling gaps with assumptions.
Which records should crypto traders collect?
Start by gathering records for the full tax period. Collect exchange transaction histories and account statements, along with the wallet addresses you used. Save original exports where possible so later reviews can be traced back to their source.
For each transaction, retain available details such as:
- Date and timestamp, including the time zone if provided.
- Asset and quantity sent or received, plus transaction identifiers.
- Available fees and records showing the U.S. dollar value used by a platform or service.
- Deposit, withdrawal, and transfer records that help connect activity between accounts and wallets.
How can traders spot gaps before preparing a return?
Reconcile records in a deliberate sequence. Compare platform exports with wallet activity, then match outgoing transactions to corresponding deposits or activity elsewhere. For U.S. federal tax reporting, a transfer without a matching destination record is a question to investigate, not something to label automatically as a sale.
A practical workflow for crypto tax for traders can look like this:
- Gather: Download exchange histories and statements, and list the wallets used during the period.
- Preserve: Keep source files unchanged and note when and where each file came from.
- Combine: Bring records into one transaction log while retaining the original platform or wallet reference.
- Match: Compare timestamps, asset quantities, transaction IDs, and available fee details across sources.
- Review: Check for missing histories, duplicate imports, unexplained asset movements, and incomplete acquisition details that may affect cost basis.
- Document exceptions: List unresolved basis, valuation, ownership, or transaction-type questions, and note which records you checked.
Keep review notes alongside the supporting files. If you adjust or categorize an entry, record the reason and evidence so a preparer can follow how you reached the reported information. Confirm uncertain U.S. federal tax treatment with the IRS or a qualified tax professional.
If several platforms, wallets, or on-chain transactions make reconciliation difficult, consider asking about crypto tax filing support from Block3 Finance.
When specialist crypto tax filing support can help U.S. traders
Specialist review may be useful when your U.S. federal tax records span several exchanges and wallets, include complex on-chain activity, or have gaps you can’t resolve from the available history. A preparer can review how the records fit together, identify open questions, and explain which assumptions may need confirmation against current IRS guidance.
Look for experience working with exchange exports, blockchain records, and transaction reconciliation. A clear review should distinguish verified information from estimates or unresolved items, explain the reasoning behind assumptions, and keep its scope focused on applicable U.S. federal rules.
Block3 Finance provides crypto tax filing and reporting, including specialized reporting for complex on-chain activity. For additional background, consult this cryptocurrency tax filing guide, and confirm current filing details with the IRS.
How can traders prepare for a tax consultation?
A well-organized file helps a tax preparer understand what you can substantiate and where the record remains incomplete. Before a consultation, assemble:
- Exchange transaction exports and account statements for the period under review.
- Wallet records, addresses, and available transaction identifiers for on-chain activity.
- Prior tax filings and any digital asset tax documents you received.
- A concise list of unresolved questions, such as missing acquisition history, uncertain cost basis, or a transfer with no matching destination record.
Note which platforms provided complete records and where data is missing or unavailable. Keep original source files alongside your reconciliation notes, and don’t present an uncertain transaction classification as settled. This gives a preparer a practical starting point, though incomplete records may not always be reconstructable.
If your records are spread across platforms or include activity that’s difficult to reconcile, specialist crypto tax filing support may help you assess next steps. Ask how the review will handle incomplete data, document assumptions, and distinguish U.S. federal tax guidance from other considerations.
Discuss your crypto tax reporting needs with Block3 Finance.
Build a clearer path through your crypto tax records
For U.S. federal reporting, the practical priorities are to assess transactions based on their facts, avoid assuming frequent trading establishes a special tax status, and keep records that trace each reported figure to its source. That foundation can make crypto tax for traders easier to review, especially when activity spans multiple platforms or wallets.
When transaction histories are incomplete or on-chain activity is complex, specialist review may help you identify gaps and prepare clearer records. Block3 Finance provides crypto tax filing and reporting, including support for complex on-chain activity. The firm serves more than 980 clients globally and brings over 13 years of blockchain financial expertise.
Discuss your crypto tax reporting needs with Block3 Finance. Organized records and specialist support can help you approach U.S. federal tax reporting with greater clarity.
Frequently Asked Questions
Is crypto trading taxable in the United States?
It can be, depending on the transaction. Under U.S. federal tax rules, selling digital assets for cash, exchanging one asset for another, or spending crypto may require gain-or-loss analysis. Receiving digital assets as income can raise separate reporting questions. Buying crypto with cash or transferring it between wallets you own is generally treated differently. Keep records and confirm how specific activity should be reported with current IRS guidance.
Does frequent crypto trading make me a trader for tax purposes?
No. Under U.S. federal rules, frequent trading alone doesn’t automatically establish a distinct tax classification. The word “trader” may simply describe what you do, while tax treatment depends on applicable rules and your circumstances. Trading activity, its purpose, and consistent records may be relevant to a professional review, but no single trade count guarantees a status or benefit. Ask a qualified tax professional to assess your facts and verify current IRS guidance.
How do I calculate crypto trading gains and losses?
Generally, compare the proceeds from a disposition with the asset’s cost basis, the amount used in gain-or-loss analysis. For U.S. federal tax purposes, proceeds may be the value received, while basis generally relates to the asset’s acquisition cost. Fees, valuation details, and the applicable basis method can affect the calculation. Preserve transaction-level records and have uncertain valuations or method choices reviewed against current IRS guidance.
Do I have to report crypto-to-crypto trades to the IRS?
Generally, a crypto-to-crypto exchange should be reviewed as a potential taxable disposition under U.S. federal tax rules, even though you didn’t receive cash. Record what you gave up, what you received, the transaction date, and the relevant values and basis information. Reporting details depend on the transaction and current IRS requirements. Don’t assume that keeping the proceeds in crypto means the exchange is outside tax reporting.
Can I deduct crypto trading losses on my U.S. tax return?
Possibly, but the treatment depends on how the loss is characterized and the rules that apply to your activity under U.S. federal tax law. A loss on a digital asset transaction doesn’t automatically mean you can deduct the full amount in any way you choose. Keep supporting records and have the loss reviewed alongside your overall tax circumstances. Confirm current IRS rules with a qualified tax professional before claiming a deduction.
What records should crypto traders keep for tax reporting?
For U.S. federal tax preparation, keep exchange histories and statements, wallet addresses, and records of purchases, sales, exchanges, deposits, withdrawals, and transfers. Preserve dates and timestamps, asset quantities, transaction IDs, available fees, and U.S. dollar valuation details. Retain original source files and notes explaining how you matched records across platforms. Flag missing cost basis, duplicate imports, and unclear transactions instead of filling gaps with assumptions.
Should I use crypto tax software or hire a specialist?
Software may help organize imports, but it can’t resolve every incomplete record or determine the right treatment for every transaction. For crypto tax for traders, specialist review may be useful when activity spans several platforms or wallets, involves complex on-chain transactions, or leaves unanswered basis or classification questions. Prepare your source files and an exception list, then confirm the preparer’s U.S. federal tax scope and approach.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
What does crypto tax for traders mean under U.S. rules?
It means reviewing the tax reporting questions connected to trading activity under U.S. federal rules. That activity may involve multiple assets, centralized exchanges, self-custody wallets, and on-chain transactions. To build a complete picture, you may need to reconcile records from more than one source. This section covers U.S. federal considerations only. It isn’t a substitute for advice based on your circumstances, and it doesn’t address state-specific tax rules.
Which trading activity should readers bring into scope?
Start with purchases, sales, exchanges, and relevant on-chain activity. A transfer between wallets you control is generally different from a transaction that changes who owns the asset, but you’ll need records to establish what happened. Preserve transaction details rather than assuming a platform label fully explains the activity. Staking, mining, airdrops, NFTs, and decentralized finance (DeFi) can involve distinct facts and tax questions. Include them in your review, but don’t assume every transaction in these categories receives the same treatment. When details are unclear, keep the supporting records and confirm the current U.S. federal treatment with the IRS or a qualified tax professional. For U.S. federal tax preparation, a transaction needs enough detail to show what moved, when it moved, and what value was involved. The IRS treats digital assets as property, and its U.S. federal tax guidance is a starting point for understanding reporting responsibilities. The treatment of an individual transaction still depends on its facts. Build a transaction-level record rather than relying on a year-end account balance. Where available, save the asset and quantity, date and time, transaction type, platform or wallet, transaction identifier, U.S. dollar value, and related fees. These details can help connect an exchange record to an on-chain movement and show where information needs review. Consistent transaction-level records give a tax preparer a traceable account of what happened, making it easier to evaluate each transaction under applicable U.S. federal rules.
How do proceeds and cost basis fit together?
Proceeds are the value received in a transaction. Cost basis is the amount used to assess an asset’s gain or loss for tax purposes. In general, a realized gain or loss is the difference between proceeds and basis when an asset is disposed of. Check current IRS guidance for the precise calculation and treatment. Fees, transaction timing, and how an asset’s value was determined may affect the records needed for analysis. Don’t assume one cost-basis method applies to every situation. Preserve acquisition and disposition details so the appropriate approach can be verified for your circumstances. Hypothetical example: A trader acquires a digital asset on one platform, later exchanges it for a different asset through a wallet, and pays a network fee. The acquisition record, exchange details, fee information, timestamps, and transaction identifier can help a preparer reconstruct the activity. This example illustrates recordkeeping only; it doesn’t determine tax treatment or predict anyone’s tax liability.
Why can exchange and blockchain records tell different parts of the story?
An exchange export may show trades completed on that platform but omit activity through another wallet or service. Blockchain records can help document transfers and transactions, but a transaction hash alone doesn’t establish the full tax context, such as who controlled the wallet or why the assets moved. Where available, compare timestamps, asset quantities, transaction identifiers, and wallet ownership across records. If activity spans several platforms or the records don’t reconcile, a crypto tax professional can help review the information. You can discuss crypto tax reporting support with Block3 Finance. No. Frequent crypto trading alone doesn’t automatically establish a special tax status under U.S. federal rules. “Trader” may simply describe someone who trades often. A tax classification is a separate question that depends on the applicable rules and the facts of the person’s activity. This distinction matters because crypto tax for traders isn’t determined by trade count alone. A high volume of transactions can make thorough records especially important, but it doesn’t guarantee a particular classification or tax outcome. For broader background on crypto trading activity and related reporting considerations, see Bloomberg Tax, and confirm specific U.S. federal treatment with current IRS guidance and a qualified tax professional.
How is trading activity different from tax classification?
Activity level is one fact to review, not a conclusion by itself. A professional may need to consider the purpose and consistency of the activity, the records available, and the taxpayer’s circumstances under relevant U.S. federal rules. Keep evidence that helps explain your activity, such as transaction histories, account records, and how you tracked trading decisions. Don’t rely on a label you use for yourself or assume that one pattern of activity automatically qualifies. Any classification should be assessed against current authoritative guidance and your full facts.
What should traders know about a possible mark-to-market election?
Section 475(f) of the U.S. Internal Revenue Code is associated with a mark-to-market election in certain trader tax contexts. Mark-to-market generally refers to valuing assets at market value for tax purposes, but that brief description doesn’t establish whether the provision applies to a particular crypto trader or asset. Treat Section 475(f) as a specialist-review question, not a default treatment. Don’t assume eligibility, timing, procedure, or tax consequences based on general online summaries. The election’s relevance depends on the taxpayer’s facts and applicable U.S. rules, so confirm current requirements with the IRS and a qualified tax professional before acting. For U.S. federal tax preparation, the goal is to turn activity across platforms and wallets into a traceable transaction history. Follow a consistent workflow, preserve original files, and record unresolved questions rather than filling gaps with assumptions.
Which records should crypto traders collect?
Start by gathering records for the full tax period. Collect exchange transaction histories and account statements, along with the wallet addresses you used. Save original exports where possible so later reviews can be traced back to their source. For each transaction, retain available details such as:
How can traders spot gaps before preparing a return?
Reconcile records in a deliberate sequence. Compare platform exports with wallet activity, then match outgoing transactions to corresponding deposits or activity elsewhere. For U.S. federal tax reporting, a transfer without a matching destination record is a question to investigate, not something to label automatically as a sale. A practical workflow for crypto tax for traders can look like this: Keep review notes alongside the supporting files. If you adjust or categorize an entry, record the reason and evidence so a preparer can follow how you reached the reported information. Confirm uncertain U.S. federal tax treatment with the IRS or a qualified tax professional. If several platforms, wallets, or on-chain transactions make reconciliation difficult, consider asking about crypto tax filing support from Block3 Finance. Specialist review may be useful when your U.S. federal tax records span several exchanges and wallets, include complex on-chain activity, or have gaps you can’t resolve from the available history. A preparer can review how the records fit together, identify open questions, and explain which assumptions may need confirmation against current IRS guidance. Look for experience working with exchange exports, blockchain records, and transaction reconciliation. A clear review should distinguish verified information from estimates or unresolved items, explain the reasoning behind assumptions, and keep its scope focused on applicable U.S. federal rules. Block3 Finance provides crypto tax filing and reporting, including specialized reporting for complex on-chain activity. For additional background, consult this cryptocurrency tax filing guide, and confirm current filing details with the IRS.
How can traders prepare for a tax consultation?
A well-organized file helps a tax preparer understand what you can substantiate and where the record remains incomplete. Before a consultation, assemble: Note which platforms provided complete records and where data is missing or unavailable. Keep original source files alongside your reconciliation notes, and don’t present an uncertain transaction classification as settled. This gives a preparer a practical starting point, though incomplete records may not always be reconstructable. If your records are spread across platforms or include activity that’s difficult to reconcile, specialist crypto tax filing support may help you assess next steps. Ask how the review will handle incomplete data, document assumptions, and distinguish U.S. federal tax guidance from other considerations. Discuss your crypto tax reporting needs with Block3 Finance. For U.S. federal reporting, the practical priorities are to assess transactions based on their facts, avoid assuming frequent trading establishes a special tax status, and keep records that trace each reported figure to its source. That foundation can make crypto tax for traders easier to review, especially when activity spans multiple platforms or wallets. When transaction histories are incomplete or on-chain activity is complex, specialist review may help you identify gaps and prepare clearer records. Block3 Finance provides crypto tax filing and reporting, including support for complex on-chain activity. The firm serves more than 980 clients globally and brings over 13 years of blockchain financial expertise. Discuss your crypto tax reporting needs with Block3 Finance. Organized records and specialist support can help you approach U.S. federal tax reporting with greater clarity.
Is crypto trading taxable in the United States?
It can be, depending on the transaction. Under U.S. federal tax rules, selling digital assets for cash, exchanging one asset for another, or spending crypto may require gain-or-loss analysis. Receiving digital assets as income can raise separate reporting questions. Buying crypto with cash or transferring it between wallets you own is generally treated differently. Keep records and confirm how specific activity should be reported with current IRS guidance.
Does frequent crypto trading make me a trader for tax purposes?
No. Under U.S. federal rules, frequent trading alone doesn’t automatically establish a distinct tax classification. The word “trader” may simply describe what you do, while tax treatment depends on applicable rules and your circumstances. Trading activity, its purpose, and consistent records may be relevant to a professional review, but no single trade count guarantees a status or benefit. Ask a qualified tax professional to assess your facts and verify current IRS guidance.
How do I calculate crypto trading gains and losses?
Generally, compare the proceeds from a disposition with the asset’s cost basis, the amount used in gain-or-loss analysis. For U.S. federal tax purposes, proceeds may be the value received, while basis generally relates to the asset’s acquisition cost. Fees, valuation details, and the applicable basis method can affect the calculation. Preserve transaction-level records and have uncertain valuations or method choices reviewed against current IRS guidance.
Do I have to report crypto-to-crypto trades to the IRS?
Generally, a crypto-to-crypto exchange should be reviewed as a potential taxable disposition under U.S. federal tax rules, even though you didn’t receive cash. Record what you gave up, what you received, the transaction date, and the relevant values and basis information. Reporting details depend on the transaction and current IRS requirements. Don’t assume that keeping the proceeds in crypto means the exchange is outside tax reporting.
Can I deduct crypto trading losses on my U.S. tax return?
Possibly, but the treatment depends on how the loss is characterized and the rules that apply to your activity under U.S. federal tax law. A loss on a digital asset transaction doesn’t automatically mean you can deduct the full amount in any way you choose. Keep supporting records and have the loss reviewed alongside your overall tax circumstances. Confirm current IRS rules with a qualified tax professional before claiming a deduction.
What records should crypto traders keep for tax reporting?
For U.S. federal tax preparation, keep exchange histories and statements, wallet addresses, and records of purchases, sales, exchanges, deposits, withdrawals, and transfers. Preserve dates and timestamps, asset quantities, transaction IDs, available fees, and U.S. dollar valuation details. Retain original source files and notes explaining how you matched records across platforms. Flag missing cost basis, duplicate imports, and unclear transactions instead of filling gaps with assumptions.
Should I use crypto tax software or hire a specialist?
Software may help organize imports, but it can’t resolve every incomplete record or determine the right treatment for every transaction. For crypto tax for traders, specialist review may be useful when activity spans several platforms or wallets, involves complex on-chain transactions, or leaves unanswered basis or classification questions. Prepare your source files and an exception list, then confirm the preparer’s U.S. federal tax scope and approach.