Does a blockchain fork create taxable income if you never receive coins you can use? For U.S. taxpayers, crypto hard fork tax treatment depends on more than a network announcement. It may hinge on whether you received a new asset and when you gained “dominion and control,” meaning the ability to transfer, sell, exchange, or otherwise dispose of it.
It’s understandable to assume that a chain split automatically puts a taxable asset in your hands. But a new chain’s existence doesn’t necessarily mean you can access its coins, and that distinction can affect whether income is recognized and how the event should be documented under U.S. federal tax guidance.
This guide explains how IRS guidance distinguishes a hard fork from receiving a new asset, which access and timing facts may matter, and how fair market value can affect income and cost basis. You’ll also learn what records, such as wallet and exchange history and valuation evidence, can support accurate reporting and a defensible filing.
Key Takeaways
- Distinguish a blockchain protocol change from a split that creates a separate digital asset before assessing a fork event.
- Under U.S. IRS guidance, crypto hard fork tax treatment may depend on whether you can access and use the new asset, not just whether a fork occurred.
- Compare wallet and exchange access, custody details, and timing to identify facts that may need tax review.
- Preserve event dates, wallet or platform records, access dates, and contemporaneous statements to support U.S. tax preparation.
- Organized records can help a tax professional review fork activity alongside your other digital asset transactions.
What Is a Crypto Hard Fork Under U.S. Tax Rules?
A crypto hard fork is a change to a blockchain’s protocol that can cause the network to split into separate versions that no longer follow the same rules. Under U.S. federal tax rules, that network event is distinct from receiving a new cryptocurrency. An announcement or split alone doesn’t establish whether, or when, a holder can access a separate asset.
That distinction frames the crypto hard fork tax treatment analysis. IRS Notice 2014-21 treats virtual currency as property for U.S. federal tax purposes, while Revenue Ruling 2019-24 addresses the tax consequences of a hard fork followed by an airdrop. The facts around the particular fork and a holder’s ability to access the resulting asset still matter.
How a blockchain split can create a new crypto asset
Blockchains rely on shared protocol rules to record and validate transactions. If a group of network participants adopts incompatible rules, the chains may diverge. Each can continue operating independently, with its own transaction history after the split and potentially its own token.
Bitcoin and Bitcoin Cash offer a historical example of a split that resulted in separate networks and assets. That example isn’t a universal template. Some protocol changes don’t create a lasting split or a separately usable asset, and the technical outcome depends on how network participants implement and support the change.
A new network can exist without making its asset available to everyone who held the original cryptocurrency. A holder might control their own wallet but need compatible software or another technical step to interact with the new chain. If an exchange or custodian holds the original coins, the platform may determine whether and when the holder can access any forked asset.
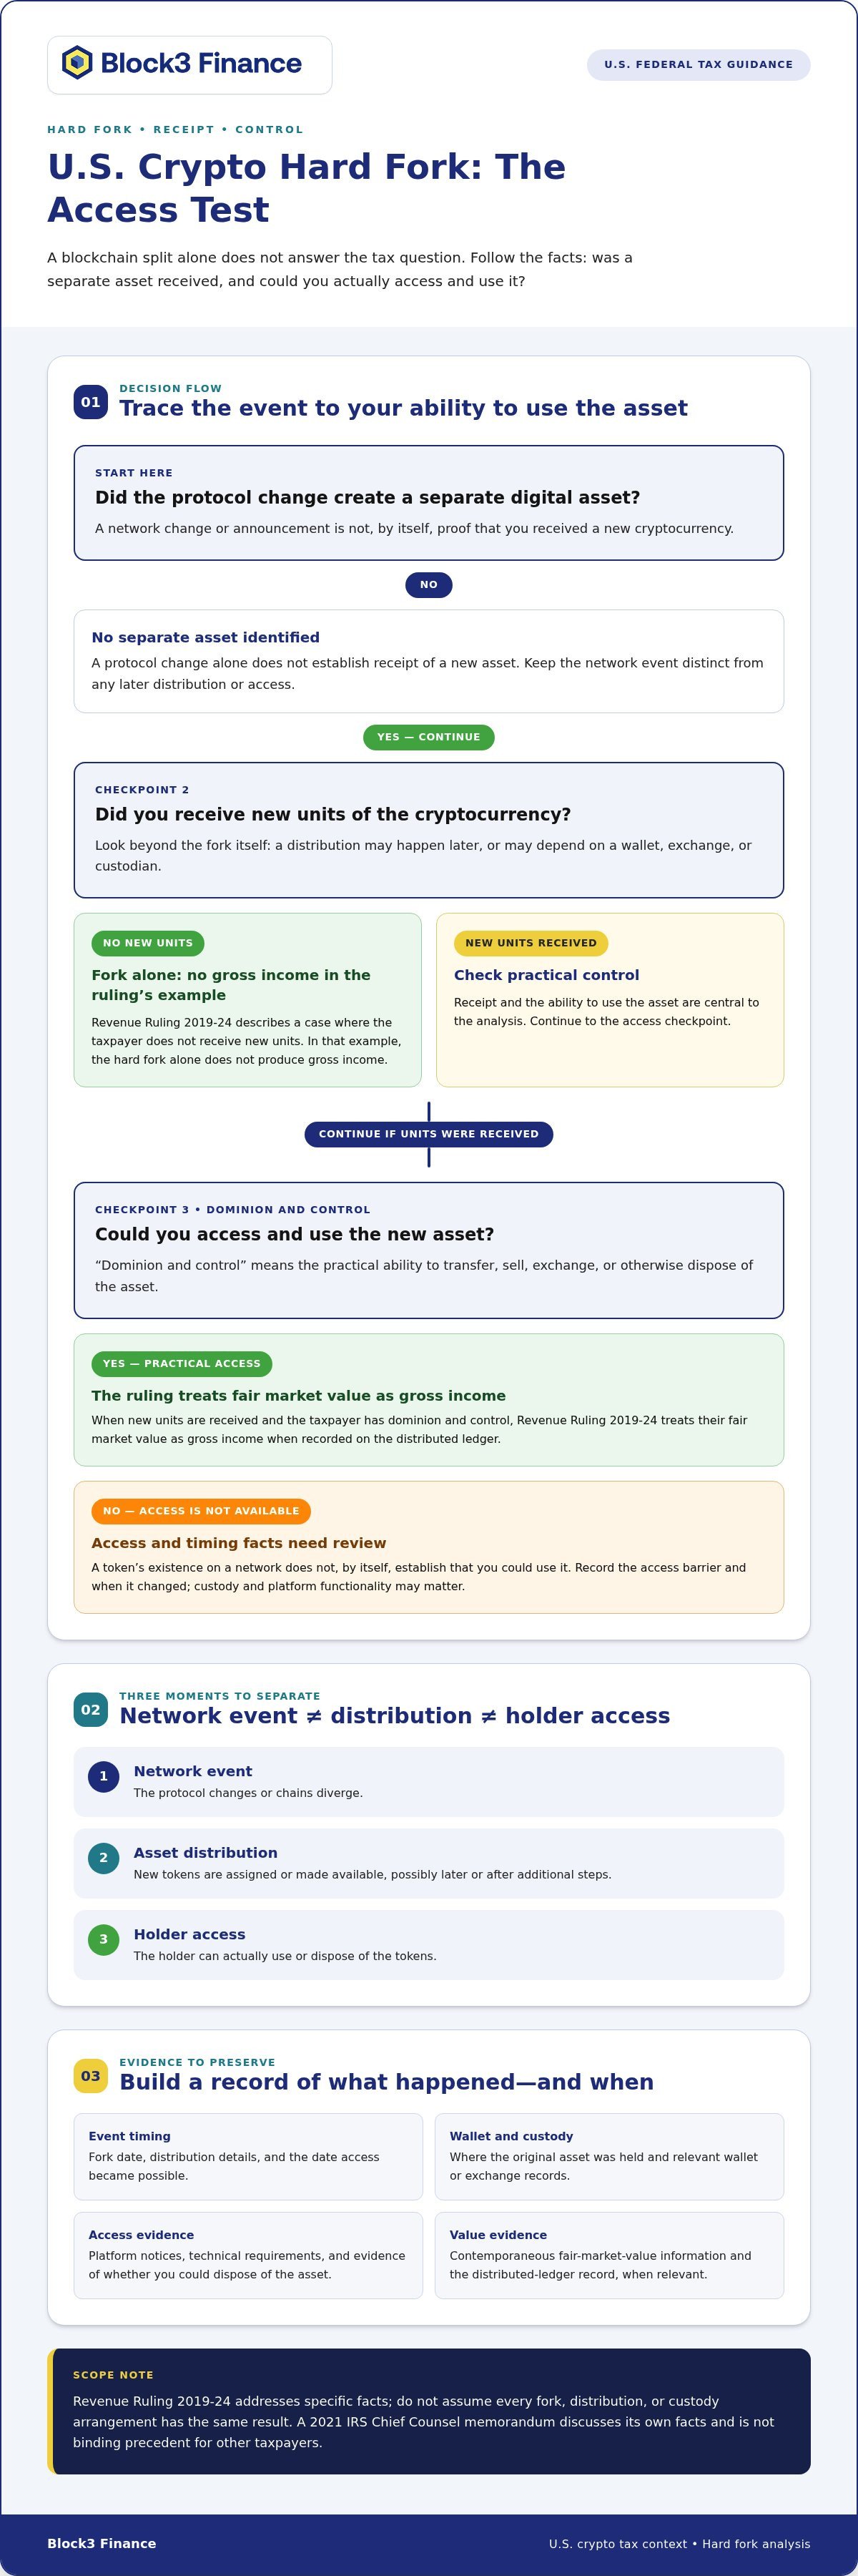
For U.S. federal tax preparation, separate the network timeline from the holder’s timeline:
- Network event: The protocol changes or chains diverge.
- Asset distribution: New tokens are assigned or made available.
- Holder access: The holder can actually use or dispose of the tokens.
Hard fork, airdrop, and receipt are not interchangeable terms
A hard fork describes a blockchain network event. An airdrop describes a distribution of tokens to specified addresses or users. A fork may happen without an immediate distribution, and a distribution may occur later or require a wallet, exchange, or custodian to take additional steps before the holder can use the asset.
These terms shouldn’t be treated as synonyms in a U.S. tax analysis. Revenue Ruling 2019-24 considers a hard fork followed by an airdrop, but a fork doesn’t mean every holder automatically receives a usable token. Nor should one event’s tax outcome be applied mechanically to another: distribution methods, custody arrangements, and practical access can differ.
Keep evidence tied to the event. Records of the original asset’s location, the fork date, platform notices, and any later access can help clarify what happened. Organized crypto tax filing and reporting can bring those details into a coherent U.S. federal tax record.
How IRS Guidance Connects a Hard Fork to Taxable Income
For U.S. federal tax purposes, the key question isn’t simply whether a blockchain split occurred. IRS guidance focuses on whether a taxpayer received new cryptocurrency and had dominion and control over it, meaning the practical ability to access and use the asset. The details matter.
It’s also important to distinguish published guidance from internal legal advice. A revenue ruling states the IRS’s published interpretation of federal tax law applied to specific facts. A Chief Counsel memorandum is legal advice prepared within the IRS. It may help explain the agency’s analysis, but it isn’t a statute or published ruling and generally can’t be relied on as precedent by other taxpayers.
What Revenue Ruling 2019-24 says about a fork followed by an airdrop
IRS Revenue Ruling 2019-24 addresses a hard fork followed by an airdrop, a distribution of cryptocurrency to a taxpayer. In the ruling’s example where the taxpayer doesn’t receive new units, the hard fork alone doesn’t produce gross income, meaning income counted for tax purposes. Where the taxpayer receives new units and has dominion and control, the ruling treats their fair market value, or market price, when recorded on the distributed ledger as gross income.
The ruling links receipt with control. A new token appearing on a network isn’t necessarily enough to show that a particular taxpayer received it; the taxpayer’s ability to access and use it is relevant. For example, a platform’s records and functionality may help establish whether a customer could actually dispose of the asset.
This is U.S. federal guidance, and its conclusions should be applied to the facts it addresses rather than assumed to resolve every fork, custody arrangement, or distribution method. The ruling doesn’t make every network split taxable, nor does it establish that every token distribution has the same outcome. Keep the specific event’s records available for review.
What the 2021 IRS memorandum adds, and what it doesn’t
A 2021 IRS Chief Counsel memorandum is also discussed in connection with a hard fork that doesn’t result in a taxpayer receiving new cryptocurrency. Its analysis is commonly cited for the view that a fork by itself, without receipt of a new asset, doesn’t create income. Treat that discussion cautiously: the memorandum addresses its own facts and isn’t binding precedent for other taxpayers.
The memorandum can inform how the IRS has analyzed a standalone fork, but it doesn’t replace Revenue Ruling 2019-24 or extend that ruling to every situation. Together, these sources make documentation important: preserve platform notices, wallet information, and evidence of when the asset became usable, then assess the facts under U.S. federal guidance.
For context on broader U.S. cryptocurrency reporting, see this U.S. cryptocurrency taxation guide. Block3 Finance’s crypto tax filing and reporting can help organize complex digital asset activity. If access or custody records leave material questions unresolved, discuss your tax reporting needs.
U.S. Hard Fork Scenarios: When Access Changes the Analysis
For U.S. federal tax purposes, a token’s existence on a blockchain and a taxpayer’s ability to use it are separate facts. The scenarios below help organize the questions, but they’re analytical aids, not automatic tax conclusions. IRS Revenue Ruling 2019-24 addresses receipt and dominion and control in the specific context of a hard fork followed by an airdrop; individual facts still require review.
Compare what happened technically with what you could actually do, and preserve records that show both.
| Scenario | Access and custody | Useful evidence | Question for U.S. tax review |
|---|---|---|---|
| Forked asset is immediately usable | You control a compatible wallet, and the new asset appears available to transfer or otherwise use. | Wallet records, transaction history, network data, and evidence of when the asset became accessible. | Do the facts show receipt and dominion and control under the IRS guidance relevant to this event? |
| Exchange or custodian hasn’t enabled the asset | The platform holds the original crypto but hasn’t credited or made the forked asset available to customers. | Platform notices, account statements, support messages, and the date access was eventually enabled, if applicable. | What could you actually access or dispose of, and when, given this custody arrangement? |
| Wallet or network shows no usable balance | A separate chain may exist, but your wallet interface doesn’t show an asset you can use. | Wallet addresses, software or network details, transaction records, and evidence of credentials or access limitations. | Does the evidence establish that you received and controlled an asset, or only that a network event occurred? |
When an exchange or custodian delays support
A chain split can occur before a platform decides whether to support the new network, so the split date and customer access date may differ. Save dated notices and account statements, and record when the asset first became available to view or use. For U.S. federal reporting, don’t assume either date determines the result without evaluating the platform’s role and the applicable IRS guidance.
When a wallet shows no usable forked asset
Blockchain activity may show that tokens exist at an address without proving you can control them. Preserve wallet records and technical evidence, including the selected network and any access error. Lost credentials, an unsupported network, or disputed ownership can make the facts more complex.
The crypto hard fork tax treatment analysis should distinguish those limits from evidence of actual access, rather than treating a missing wallet display as decisive. Build a timeline with the split, any distribution, custody changes, and first practical access. That record gives a tax professional a clearer basis to assess the event under U.S. federal guidance without assuming that every holder’s outcome is the same.
How to Document and Report a U.S. Hard Fork
A defensible U.S. tax filing starts with an event record, not a guess based on a fork announcement. Build a clear timeline linking the original asset, the fork, any distribution, practical access, and any later transaction. This helps a tax preparer assess the facts under current IRS guidance.
Build an event record that supports timing and ownership
Use a consistent folder or spreadsheet for each fork, and keep original files alongside your notes. Record the original asset, wallet address or exchange account, evidence that you held the asset around the fork, and the date and time shown by each source. Save platform communications and account statements, especially if the platform enabled access after the chain split.
- Identify the event. Note the network, the original asset, the fork announcement or split date, and the source for each date.
- Document custody. Record whether the original asset was held in a self-managed wallet or with an exchange or custodian. Preserve account statements, wallet records, and relevant addresses.
- Track access. Note when the new asset first became visible and usable, if applicable. Save dated platform notices, screenshots, and transaction records that support the timeline.
- Capture valuation evidence. Preserve the source, timestamp, currency, and calculation used for any fair market value estimate. Fair market value means the asset’s value in an open market, but verify the appropriate source and measurement time against applicable U.S. IRS guidance and the specific facts.
- Keep records reviewable. Use a consistent file name and date format, retain unedited source documents, and label estimates separately from confirmed transaction data.
Separate a possible receipt event from a later disposal
Receiving or gaining access to a forked asset and disposing of it later are distinct events for U.S. tax analysis. If you later sell, exchange, or otherwise dispose of the asset, keep a separate record of the transaction date, proceeds, units involved, and any transaction fees. Don’t assume the later transaction answers whether an earlier receipt event occurred.
Before preparing a U.S. return, reconcile those event records with the rest of your wallet and exchange activity. Applicable IRS forms and instructions can change, so confirm current reporting requirements rather than relying on an old template or an assumed form. A U.S. cryptocurrency tax filing guide can provide broader context, while your fork-specific records support review of the details.
Thoughtful documentation turns uncertainty into facts a tax professional can evaluate. Block3 Finance provides crypto tax filing and reporting for digital asset activity, including complex fork records.
When Specialized U.S. Crypto Tax Support Can Help
A hard fork may be straightforward to document when one wallet shows a new asset and the access date is clear. Review becomes more involved when custody sits with a platform, records conflict, or several wallets and forked assets are involved. Specialized support can help organize the evidence and assess the event as part of your wider U.S. crypto tax reporting.
When a hard fork deserves individual review
Consider professional review when an exchange enabled access well after a chain split, when you received assets across multiple wallets, or when key records are missing. These facts can make it difficult to establish what you held, what you could access, and when. The crypto hard fork tax treatment analysis depends on the event’s details, not a single rule applied to every holder.
The right review also depends on who owns or reports the activity. An individual’s personal wallet history may raise different recordkeeping and reporting questions from a business treasury, family trust, or a DAO’s transaction activity. For cross-border holdings or estate planning involving digital wealth, advisory practices like sheikhnajam.com assist with international tax and trust administration. Keep the analysis focused on the relevant taxpayer and U.S. federal rules, and verify current IRS guidance and instructions before making a filing decision. This article offers general information, not personalized tax advice.
- Custody is unclear: An exchange or custodian may control the original assets, while its records provide limited detail about access to the forked asset.
- Several wallets are involved: Transfers between wallets can make it harder to match balances and transaction histories to one taxpayer.
- Valuation evidence is incomplete: The available price source or timestamp may not clearly support a fair market value estimate.
- Ownership is disputed: Shared access, missing credentials, or activity connected to an organization may need closer fact-specific review.
Turn complex blockchain activity into defensible tax records
Tax filing and accounting support can bring wallet data, exchange statements, transaction histories, and fork-related evidence into a consistent record set. A tax professional can then review the event alongside other digital asset activity, identify gaps or inconsistencies, and document assumptions that need further verification. Organized records don’t guarantee a particular tax result, but they make the underlying facts easier to evaluate and explain.
Block3 Finance provides crypto tax filing and reporting for complex digital asset activity. Its crypto tax filing services connect event-level documentation with broader reporting and compliance work, including a review of which records support the position taken on a return.
Before filing, bring the available facts together: who held the original asset, how it was custodied, when the new asset became accessible, and what records support any valuation or later transaction. If custody, access, or multiple wallets leave material questions unresolved, discuss your U.S. crypto tax reporting needs with Block3 Finance.
Make Your Next Reporting Decision With Confidence
A hard fork can expose gaps in how digital asset activity is tracked. Use the experience to strengthen your recordkeeping process, so future events are easier to trace, review, and incorporate into your U.S. tax preparation.
The right crypto hard fork tax treatment depends on the facts and applicable IRS guidance. If a fork involves multiple wallets, unclear custody, or incomplete records, organized documentation gives your tax professional a stronger foundation for evaluating the event alongside your other activity. For taxpayers facing unexpected liabilities or back taxes from unrecorded digital asset events, exploring IRS Fresh Start Program assistance can provide viable relief options.
Block3 Finance provides specialized tax filing and reporting for complex on-chain activity, helping bring transaction evidence into a structured, reviewable record.
For support with your U.S. crypto tax reporting, discuss your reporting needs with Block3 Finance.
Frequently Asked Questions
Is every U.S. crypto hard fork taxable?
No. Under U.S. federal guidance, a fork by itself doesn’t necessarily create taxable income. IRS Revenue Ruling 2019-24 addresses a fork followed by an airdrop and distinguishes between a taxpayer who doesn’t receive new units and one who receives them with dominion and control. For your records, identify whether a separate asset was actually distributed to you rather than relying only on a project announcement or a token’s appearance on a block explorer.
Can a U.S. taxpayer have a tax event before an exchange lists forked coins?
Possibly, because exchange listing and practical access aren’t always the same thing. A taxpayer might have control through a compatible self-custody wallet even if a particular exchange doesn’t list the asset; conversely, a platform account may show no usable balance. For U.S. federal tax analysis, document how you could access or dispose of the asset, and don’t treat a listing date as decisive without reviewing the actual custody and access facts.
What happens if a forked token becomes accessible months after a hard fork?
The later access date may be important, but it doesn’t resolve the tax result by itself. Preserve evidence showing what prevented access earlier and what changed, such as a platform notice, wallet update, or completed distribution. Compare that timeline with the facts addressed by IRS Revenue Ruling 2019-24 and current U.S. federal guidance. If records show several attempted access dates, keep them all rather than choosing one without support.
How should a U.S. taxpayer value a newly accessible forked asset?
For the hard-fork-and-airdrop facts addressed in IRS Revenue Ruling 2019-24, the ruling measures income using the asset’s fair market value when the units are recorded on the distributed ledger, provided the taxpayer has dominion and control. Keep evidence of the relevant timestamp and the U.S.-dollar price source used. If trading is limited or prices vary across platforms, document the method and have it reviewed against current IRS guidance.
Does holding the original cryptocurrency alone create income when a hard fork occurs?
Not necessarily. IRS Revenue Ruling 2019-24 describes a situation where a hard fork occurs but the taxpayer doesn’t receive new units, and says the fork alone doesn’t produce gross income in those facts. A record showing only the original asset’s balance may help explain what you held, but it won’t answer every question about a separate distribution or later access. Keep platform and wallet records that clarify whether new units reached you.
Can a U.S. business have different hard fork reporting issues from an individual?
Yes. The underlying fork facts may be similar, but a business also needs to establish which entity owned or controlled the relevant wallet and how the activity connects to its books. For example, a company wallet, employee-controlled wallet, or DAO-related transaction may raise different ownership and record-reconciliation questions. U.S. federal reporting should reflect the taxpayer involved, so organize entity records and wallet activity separately and confirm current treatment with a qualified tax professional.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
Is every U.S. crypto hard fork taxable?
No. Under U.S. federal guidance, a fork by itself doesn’t necessarily create taxable income. IRS Revenue Ruling 2019-24 addresses a fork followed by an airdrop and distinguishes between a taxpayer who doesn’t receive new units and one who receives them with dominion and control. For your records, identify whether a separate asset was actually distributed to you rather than relying only on a project announcement or a token’s appearance on a block explorer.
Can a U.S. taxpayer have a tax event before an exchange lists forked coins?
Possibly, because exchange listing and practical access aren’t always the same thing. A taxpayer might have control through a compatible self-custody wallet even if a particular exchange doesn’t list the asset; conversely, a platform account may show no usable balance. For U.S. federal tax analysis, document how you could access or dispose of the asset, and don’t treat a listing date as decisive without reviewing the actual custody and access facts.
What happens if a forked token becomes accessible months after a hard fork?
The later access date may be important, but it doesn’t resolve the tax result by itself. Preserve evidence showing what prevented access earlier and what changed, such as a platform notice, wallet update, or completed distribution. Compare that timeline with the facts addressed by IRS Revenue Ruling 2019-24 and current U.S. federal guidance. If records show several attempted access dates, keep them all rather than choosing one without support.
How should a U.S. taxpayer value a newly accessible forked asset?
For the hard-fork-and-airdrop facts addressed in IRS Revenue Ruling 2019-24, the ruling measures income using the asset’s fair market value when the units are recorded on the distributed ledger, provided the taxpayer has dominion and control. Keep evidence of the relevant timestamp and the U.S.-dollar price source used. If trading is limited or prices vary across platforms, document the method and have it reviewed against current IRS guidance.
Does holding the original cryptocurrency alone create income when a hard fork occurs?
Not necessarily. IRS Revenue Ruling 2019-24 describes a situation where a hard fork occurs but the taxpayer doesn’t receive new units, and says the fork alone doesn’t produce gross income in those facts. A record showing only the original asset’s balance may help explain what you held, but it won’t answer every question about a separate distribution or later access. Keep platform and wallet records that clarify whether new units reached you.
Can a U.S. business have different hard fork reporting issues from an individual?
Yes. The underlying fork facts may be similar, but a business also needs to establish which entity owned or controlled the relevant wallet and how the activity connects to its books. For example, a company wallet, employee-controlled wallet, or DAO-related transaction may raise different ownership and record-reconciliation questions. U.S. federal reporting should reflect the taxpayer involved, so organize entity records and wallet activity separately and confirm current treatment with a qualified tax professional.