Crypto isn’t tax-free simply because it stays on a blockchain. For U.S. federal tax purposes, the IRS treats cryptocurrency as property under Notice 2014-21, and selling, swapping, or spending it can trigger a taxable event. Effective crypto tax optimization strategies start with knowing when a transaction creates income or a capital gain, and what records support your tax return.
If airdrops, staking rewards, charitable giving, or a plan to sell appreciated crypto have made your tax picture harder to manage, that’s understandable. The tax treatment depends on what you received or transferred, when you gained control of it, and how you use or dispose of it. Planning ahead can help you understand the consequences before you act, rather than reconstructing them at filing time.
This article explains when crypto transactions may be taxable under U.S. rules, how donating appreciated assets may affect capital gains, and how airdrops and staking rewards are generally treated. It also considers charitable remainder trusts as a possible planning structure, so you can assess which approaches may fit your circumstances and where careful tax reporting matters.
Key Takeaways
- Identify which crypto transactions may create taxable income or gains before planning a sale, swap, or charitable transfer.
- Capital losses may offset realized gains, so accurate transaction records can help clarify your tax position.
- Donating appreciated cryptocurrency may affect capital-gains tax, while the IRS requires a qualified appraisal to substantiate noncash charitable deductions worth more than $5,000.
- Airdrops and staking rewards may count as ordinary income when you gain control of them; lending activity and interest also need careful classification.
- Understand how cost-basis records, Form 1099-DA reporting, and trust structures fit together before choosing a tax-planning approach.
Do You Have to Pay Taxes on Crypto in the U.S.?
Yes. For U.S. federal tax purposes, the IRS treats cryptocurrency as property under Notice 2014-21. Selling crypto, swapping it for another token, or spending it can create a taxable event. A transfer between wallets you own generally doesn’t have the same tax effect. The key question is whether a transaction changes ownership or produces income.
Holding time affects the rate on a capital gain, the profit from a sale. Crypto held for more than 365 days may qualify for long-term rates of 0%, 15%, or 20%. For 2026, the 0% threshold is $49,450 for single filers, $66,200 for heads of household, and $98,900 for married couples filing jointly. The 20% rate generally applies above $545,500, $579,600, and $613,700, respectively. Short-term gains on assets held for 12 months or less are taxed at ordinary income rates, ranging from 10% to 37% in 2026. Effective crypto tax optimization strategies account for holding periods before a sale.
Holding crypto for more than 365 days can qualify a gain for long-term treatment; a shorter holding period generally means short-term treatment. Specific identification records which units you sold, while first-in, first-out (FIFO) treats the earliest acquired units as sold when you don’t identify units. Keep records supporting the units selected, their cost basis, generally the amount paid to acquire them, and sale proceeds. For investors looking to build their trading skills and better time these market moves, Moonstream Finance offers an educational community focused on cryptocurrency investing and asset management.
Tax-loss harvesting means selling crypto at a loss to offset realized capital gains. For U.S. taxpayers, capital losses may offset realized gains, and losses exceeding gains may allow a deduction of up to $3,000 from taxable income for the year, according to the Internal Revenue Service. Unused capital losses may carry forward to future years indefinitely. These crypto tax optimization strategies depend on accurate transaction and basis records.
The Internal Revenue Service says capital gains are reported on Schedule D (Form 1040), and Form 8949 may need to be completed first. Organized records help connect each disposal to its proceeds and cost basis for federal reporting.
Gifting crypto can involve a separate filing obligation. In the United States, gifts worth more than $19,000 per recipient in 2026 require the giver to submit a gift tax return, according to the Internal Revenue Service. For U.S. crypto tax reporting, distinguish gift records from sales and other taxable transactions.
Charitable Donations of Cryptocurrency Under IRS Rules
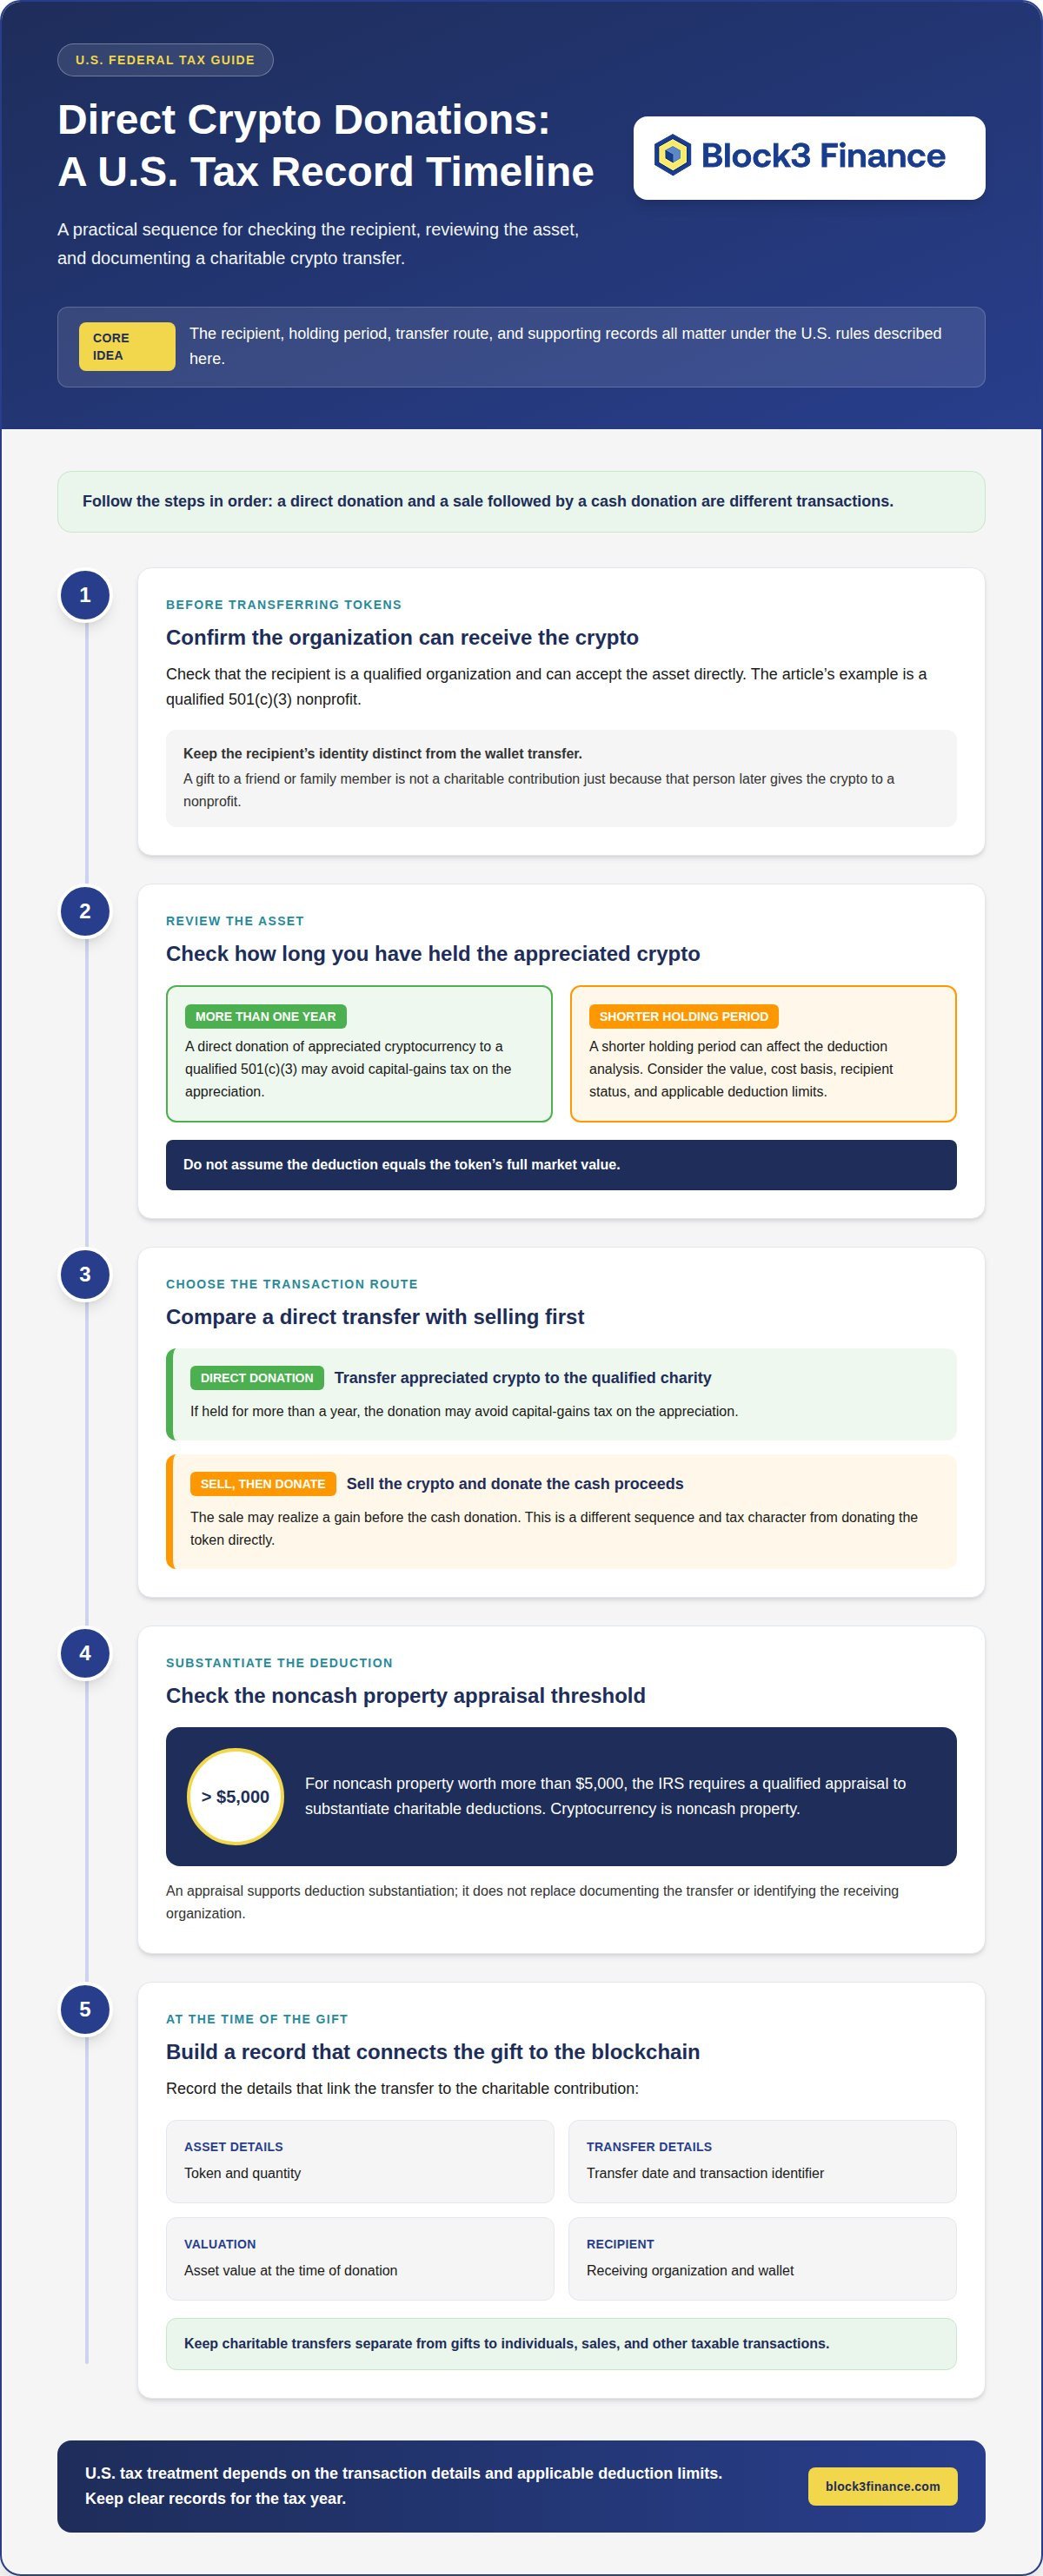
A direct crypto donation may support a qualified U.S. charity while affecting your federal tax position. Donating appreciated cryptocurrency held for more than a year directly to a 501(c)(3) nonprofit can avoid capital-gains tax on its appreciation. Selling the asset first and donating the proceeds is a different transaction: the sale may realize a gain before the cash donation.
For noncash property worth more than $5,000, the Internal Revenue Service requires a qualified appraisal to substantiate charitable deductions. Cryptocurrency is noncash property, so a donation exceeding that threshold calls for appraisal support. The appraisal is part of the deduction substantiation, not a substitute for documenting the transfer or identifying the receiving organization.
Before transferring tokens, confirm that the recipient is a qualified organization and can accept the asset directly. Record the token, quantity, transfer date, transaction identifier, and the asset’s value at the time of donation. These details link the blockchain transaction to the charitable gift and support your tax records for that year.
The holding period matters. Under the stated U.S. treatment, a donor who contributes appreciated crypto after holding it for more than a year may avoid capital-gains tax on the appreciation. A shorter holding period can affect the deduction analysis. The value, cost basis, recipient status, and applicable deduction limits all matter, so don’t assume the deduction equals the token’s full market value.
Consider an example: you acquired one token at a lower value, held it for more than a year, and it appreciated before a direct transfer to a 501(c)(3). The contribution may avoid capital-gains tax on that appreciation. Donating the token, rather than selling it and donating cash, changes the sequence and tax character of the transaction. Crypto and stocks may both appreciate, but digital-asset transfer records require careful matching to the gift.
A gift to a friend or family member is not the same as a charitable donation. It doesn’t qualify as a charitable contribution simply because the recipient later gives the crypto to a nonprofit. Keep separate records for gifts, charitable transfers, and sales, including the receiving wallet and transaction hash. These records help distinguish a donation from a taxable sale or exchange when preparing U.S. tax records.
Is Avoiding Crypto Tax Legal Under U.S. Rules?
Lawful planning means reporting transactions accurately and applying the tax rules that govern them. Hiding crypto sales or omitting income is underreporting, not tax optimization. Underreported tax can lead to additional tax, interest, and penalties. During an IRS examination, transaction records may be compared with information returns, and taxpayers may need to substantiate reported proceeds and cost basis.
Cost basis is what you paid for an asset, adjusted where applicable; it helps calculate gain or loss when selling. Since January 1, 2025, U.S. digital-asset records track basis wallet by wallet rather than pooling units across wallets. Keep purchase dates, amounts, transaction records, wallet details, and transfers together. For example, bitcoin moved between your own wallets should not lose its original basis history.
If you don’t identify the units sold, the method used to determine which units were sold can affect the tax calculation. FIFO treats the earliest-acquired units as sold first. Specific identification instead records the particular units selected for a sale. Keep records supporting that selection, including acquisition and sale details, so the reported calculation follows the method used.
Form 1099-DA adds broker reporting for digital-asset transactions. For the 2025 tax year, brokers report gross proceeds from digital-asset sales or exchanges. Cost-basis reporting generally begins for 2026 transactions involving covered assets. For crypto bought on a broker’s platform on or after January 1, 2026, brokers must include basis on Form 1099-DA. Reconcile broker information with wallet-level records rather than assuming it captures every transaction.
Gifting crypto may affect the recipient’s basis and future tax calculation. A lifetime gift generally does not receive a basis increase under Sec. 1014; that rule generally applies to property inherited after the owner’s death. Record the transfer, asset, and relevant basis details. A contribution to someone else differs from selling crypto yourself, but it doesn’t erase the need for clear records.
A normal crypto pledge used as loan collateral generally doesn’t trigger gain or loss when the borrower receives loan proceeds. That treatment differs from selling bitcoin to raise cash. Distinguishing a loan from a sale, documenting specific identification, and reconciling Form 1099-DA data help support accurate U.S. reporting and protect your records if the IRS examines a return.
Are Airdrops and Staking Rewards Taxable Income?
U.S. taxpayers generally recognize airdrop and staking rewards as ordinary income once they gain dominion and control over the tokens. That means they can use, transfer, or otherwise dispose of them. A notification alone doesn’t establish control. Record when the tokens became accessible, their value at that time, and any later sale as a separate tax event.
Mining, staking, airdrop, and hard-fork income may be reported on Form 1099-MISC. The form is a reporting record, not a replacement for tracking the underlying digital asset activity. Compare reported amounts with wallet and platform records, including the date received and the asset’s value. A mismatch can affect reported taxable income and the token’s basis for a later sale.
For ETH staking, Revenue Ruling 2023-14 describes the IRS position that rewards are generally ordinary income once the validator can sell, exchange, or otherwise dispose of them. The act of staking ETH as an Ethereum validator should not itself be a taxable event. Keep the staking date distinct from the date rewards become available; those events carry different tax implications.
A hard fork or airdrop requires attention to access and control, not just a blockchain announcement. Tokens that arrive but remain inaccessible differ from tokens you can use or transfer. Record the event, wallet, quantity, and date you gained control. These details help distinguish a potential income event from a later sale or exchange.
Crypto lending also has separate income considerations. Interest earned from lending cryptocurrency is taxed at ordinary income rates. Interest or other fees paid to a crypto lender during a loan term will likely be ordinary income to the recipient. Track principal separately from interest and fees: repayment of loaned assets and compensation earned are different items.
For example, if a borrower pays a lender interest in digital assets, identify the payment as interest and record its receipt date and value. The lender should also distinguish interest from returned principal in transaction records. This distinction matters even if the lender later sells the received tokens, because that sale is separate from earning the interest.
Keep income records alongside, but separate from, charitable transfer and capital-gains records. A clear timeline of mining proceeds, reward access, lending payments, and later sales supports accurate U.S. income tax reporting.
Charitable Remainder Trusts for Appreciated Crypto Under U.S. Rules
A charitable remainder trust may be considered when an investor holds appreciated cryptocurrency and wants to support charity while receiving income. The structure holds assets, pays an income stream to a beneficiary, and directs the remainder to charity under its terms. It is a specialized planning arrangement, not a simple wallet transfer or direct charitable donation.
The described strategy is aimed at investors with $1 million or more in crypto gains. That scale matters because setting up and administering a trust involves more than deciding which token to contribute. The investor needs to consider the asset’s appreciation, the trust’s payment terms, the charitable remainder, and how each step affects personal cash flow and tax reporting.
Contribution and sale are distinct stages. A digital asset may be transferred into the trust before a sale, but the capital-gains tax treatment depends on the trust structure and transaction details. Don’t assume that transferring appreciated crypto eliminates tax or makes a later sale tax-free. The holding period, cost basis, transfer documentation, and trust terms all affect the analysis.
A trust can provide an income stream for up to 20 years or for the recipient’s life expectancy. The payment schedule and beneficiary terms shape how the arrangement works over time. Before transferring crypto, map the asset’s current ownership, basis records, custody arrangements, intended charitable remainder, and planned distributions. This helps connect the original holding to later trust activity.
Reporting also requires clear records of each stage. Preserve documentation for the contribution, valuation, trust-held assets, any sale, and payments to beneficiaries. Trust administration and the investor’s individual reporting are separate considerations; the transfer alone doesn’t determine how every later transaction is treated. Keep digital-asset records aligned with trust statements and distribution details.
A charitable remainder trust is not a universal way to avoid capital-gains tax. It is a structure to evaluate when substantial appreciation, charitable intent, and a long-term income plan align. For U.S. investors, the decision should account for the asset contributed, the timing of any sale, the income arrangement, and the charitable remainder. Compare this structure with a direct crypto donation before deciding how appreciated assets will support charitable giving.
How Block3 Finance Can Help With U.S. Crypto Tax Reporting
Block3 Finance helps U.S. crypto holders align transaction records with tax reporting. This support can be useful when activity spans wallets, exchanges, staking, lending, charitable transfers, or digital-asset sales. Applying crypto tax optimization strategies starts with understanding the activity and keeping its records connected to the relevant reporting.
Tax Filing and Reporting brings taxable crypto activity into the return process. Accurate reporting depends on connecting each transaction to its date, proceeds, cost basis, and tax treatment. A crypto tax accountant can help interpret activity across multiple sources and prepare records for reporting, including when exchange summaries don’t capture every wallet transaction. This gives you a clearer basis for applying crypto tax optimization strategies to your transactions.
Audits and Compliance supports organized documentation for reported activity. For example, records for a sale should connect the asset disposed of with its acquisition details and proceeds. If an IRS examination raises questions, coherent records help explain how reported figures were calculated. This work focuses on accounting and compliance, not legal representation.
Monthly Accounting can keep your books current as crypto activity continues, rather than leaving a year’s transactions to reconstruct at filing time. It supports a consistent view of digital-asset activity, including income, transfers, and realized gains or losses. Regular accounting records also help businesses distinguish crypto transactions from other financial activity and maintain their planning approach over time.
- Tax Filing and Reporting: Organizes transaction information for U.S. tax filings.
- Audits and Compliance: Supports clear accounting records for review and compliance work.
- Monthly Accounting: Maintains financial records as crypto activity occurs.
- Crypto Tax Accountant: Helps connect digital-asset transactions with their tax reporting treatment.
These services can work together when you need both return preparation and stronger recordkeeping. A business with ongoing transactions may benefit from accounting throughout the year, while an individual preparing a return may need focused reporting support. The work is tailored to the activity and records involved, helping turn crypto tax optimization strategies into accurate reporting.
To discuss your U.S. crypto tax reporting needs, contact Block3 Finance.
Frequently Asked Questions
Do you have to pay taxes on crypto?
Yes, U.S. taxpayers may owe federal tax on crypto activity, but a taxable transaction doesn’t always mean tax is due. The outcome depends on the type of activity, its tax treatment, and the taxpayer’s overall return. Don’t assume that keeping proceeds in an exchange account or reinvesting them removes the tax consequences. Keep transaction records even when no cash reaches a bank account.
Can I deduct lost or stolen cryptocurrency?
Generally, individuals can’t deduct personal crypto theft losses under current federal rules, except for losses in a federally declared disaster area. A market decline is different from theft, and a missing password doesn’t automatically create a deductible loss. Preserve wallet records, transaction histories, and documentation describing what happened. These details help distinguish theft, loss of access, and a decline in asset value when preparing tax records.
Do airdrops and staking rewards count as income?
They generally count as U.S. ordinary income when you gain control of the tokens. For tax records, note when the tokens became available, not merely when an exchange or protocol announced a distribution. Preserve the asset quantity, wallet receipt, and value at that time. If a platform reports income on Form 1099-MISC, compare that information with your own records before preparing your return.
How is crypto taxed?
U.S. crypto activity is reported through the regular federal income tax return, not a separate crypto return. A practical first step is to classify each transaction-history entry as a receipt, transfer, or disposal. Then match records across wallets and platforms, since the same activity may appear in multiple places. This helps prevent internal transfers from being mistaken for separate income or sales.
Is avoiding crypto tax legal?
Legally reducing tax is different from hiding transactions or leaving income off a return. U.S. taxpayers can apply relevant rules and report the resulting figures accurately; concealing activity can lead to penalties, interest, or criminal prosecution. Keep records explaining how reported amounts were calculated, including source documents and transaction histories. If the IRS examines a return, those records can help support the reported figures.
What is the crypto tax rate?
There’s no single U.S. crypto tax rate. The applicable federal rate depends on whether an amount is treated as ordinary income or a capital gain, as well as taxable income and filing status. State income tax may also affect the total. For planning, separate income from asset sales in your records, then assess each category in the context of your full tax return.
What are the current U.S. federal tax rates for short-term and long-term cryptocurrency capital gains?
For 2026, U.S. short-term capital gains rates range from 10% to 37%; long-term rates are 0%, 15%, or 20%. The rate that applies depends on taxable income and filing status, so the top rate doesn’t apply to every taxpayer. Long-term thresholds differ by filing status. These are federal rates; state tax may be additional.
How are cryptocurrency sales, swaps, spending, staking, and mining taxed by the IRS?
Under U.S. federal rules, sales, swaps, and spending can create capital gains or losses, while mining and staking can produce ordinary income. For each event, retain the date, asset, quantity, and transaction record. For a swap, document both assets involved; for a purchase using crypto, keep the payment record. This creates a traceable history for classifying activity and preparing a complete tax return.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
Do you have to pay taxes on crypto?
Yes, U.S. taxpayers may owe federal tax on crypto activity, but a taxable transaction doesn’t always mean tax is due. The outcome depends on the type of activity, its tax treatment, and the taxpayer’s overall return. Don’t assume that keeping proceeds in an exchange account or reinvesting them removes the tax consequences. Keep transaction records even when no cash reaches a bank account.
Can I deduct lost or stolen cryptocurrency?
Generally, individuals can’t deduct personal crypto theft losses under current federal rules, except for losses in a federally declared disaster area. A market decline is different from theft, and a missing password doesn’t automatically create a deductible loss. Preserve wallet records, transaction histories, and documentation describing what happened. These details help distinguish theft, loss of access, and a decline in asset value when preparing tax records.
Do airdrops and staking rewards count as income?
They generally count as U.S. ordinary income when you gain control of the tokens. For tax records, note when the tokens became available, not merely when an exchange or protocol announced a distribution. Preserve the asset quantity, wallet receipt, and value at that time. If a platform reports income on Form 1099-MISC, compare that information with your own records before preparing your return.
How is crypto taxed?
U.S. crypto activity is reported through the regular federal income tax return, not a separate crypto return. A practical first step is to classify each transaction-history entry as a receipt, transfer, or disposal. Then match records across wallets and platforms, since the same activity may appear in multiple places. This helps prevent internal transfers from being mistaken for separate income or sales.
Is avoiding crypto tax legal?
Legally reducing tax is different from hiding transactions or leaving income off a return. U.S. taxpayers can apply relevant rules and report the resulting figures accurately; concealing activity can lead to penalties, interest, or criminal prosecution. Keep records explaining how reported amounts were calculated, including source documents and transaction histories. If the IRS examines a return, those records can help support the reported figures.
What is the crypto tax rate?
There’s no single U.S. crypto tax rate. The applicable federal rate depends on whether an amount is treated as ordinary income or a capital gain, as well as taxable income and filing status. State income tax may also affect the total. For planning, separate income from asset sales in your records, then assess each category in the context of your full tax return.
What are the current U.S. federal tax rates for short-term and long-term cryptocurrency capital gains?
For 2026, U.S. short-term capital gains rates range from 10% to 37%; long-term rates are 0%, 15%, or 20%. The rate that applies depends on taxable income and filing status, so the top rate doesn’t apply to every taxpayer. Long-term thresholds differ by filing status. These are federal rates; state tax may be additional.
How are cryptocurrency sales, swaps, spending, staking, and mining taxed by the IRS?
Under U.S. federal rules, sales, swaps, and spending can create capital gains or losses, while mining and staking can produce ordinary income. For each event, retain the date, asset, quantity, and transaction record. For a swap, document both assets involved; for a purchase using crypto, keep the payment record. This creates a traceable history for classifying activity and preparing a complete tax return.