Under U.S. federal tax rules, crypto losses may reduce taxable income in some situations. The Internal Revenue Service generally allows individuals to use up to $3,000 of eligible losses from crypto sales against other income. Crypto tax compliance services can help organize transaction records so sales, exchanges, payments, and rewards are reported consistently.
Crypto activity can affect your U.S. tax return even when you don’t receive cash. This guide explains how federal rules apply to crypto transactions, gifts, donations, mining, staking, airdrops, and payments. It also covers the records and tax forms involved, so you can better understand what to report and how different activities may affect your return.
Key Takeaways
- Learn how holding period and cost basis affect the gain or loss you report when disposing of crypto.
- Understand why exchanging crypto can have tax consequences even when no cash changes hands.
- See how gifts and charitable donations are treated differently from selling or spending digital assets.
- According to the Internal Revenue Service (IRS), ordinary income from digital asset forks, staking and mining is reported on Form 1040 (Schedule 1), Additional Income and Adjustments to Income.
- Explore how receiving crypto for wages, goods, or services can involve income reporting and a separate tax result when you later dispose of it.
Crypto taxes: What is cryptocurrency and how is it taxed?
Under U.S. federal rules, crypto activity can create capital gains, losses, or income, depending on the transaction. Accurate records help you apply the right tax treatment to each event.
Capital Gains and Losses
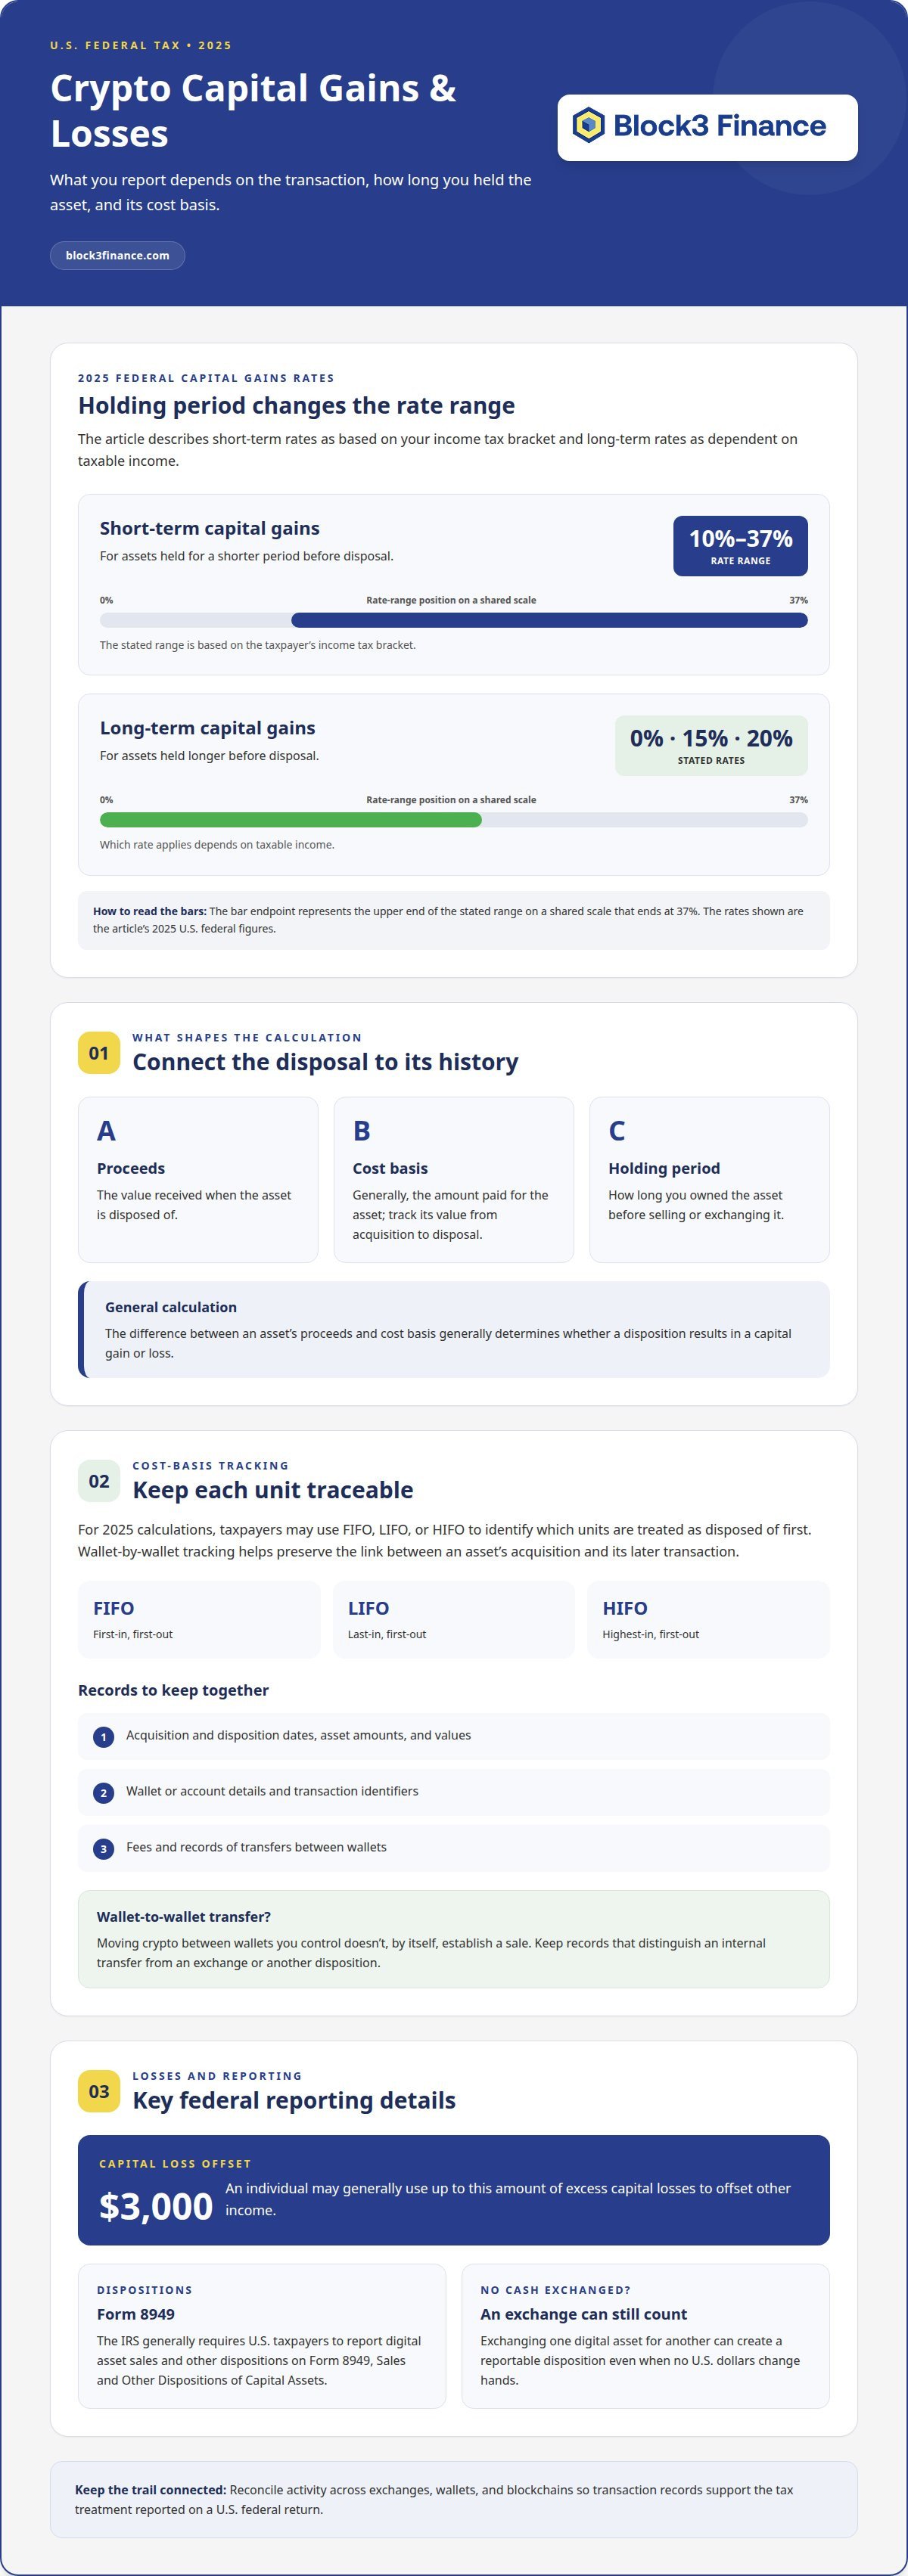
A capital gain or loss is generally the difference between an asset’s proceeds and its cost basis, usually the amount paid for it. The holding period is how long you owned the asset before disposing of it, such as by selling or exchanging it. These details help determine how to classify and report a transaction.
For 2025, U.S. federal short-term capital gains rates range from 10% to 37%, based on the taxpayer’s income tax bracket. Long-term rates are 0%, 15%, or 20%, depending on taxable income. An individual may generally use up to $3,000 of excess capital losses to offset other income, according to the Internal Revenue Service (IRS).
Cost-Basis Tracking Across Wallets
Cost-basis tracking links an asset’s value when acquired to its value when disposed of. Incomplete records can make it difficult to calculate a gain or loss accurately.
For 2025 calculations, taxpayers may use FIFO, LIFO, or HIFO methods to identify which units are treated as disposed of first. Wallet-by-wallet tracking preserves the link between each asset unit, its acquisition, and its later transaction. A record set can include:
- Acquisition and disposition dates, asset amounts, and values
- Wallet or account details and transaction identifiers
- Fees and records of transfers between wallets
Moving crypto between wallets you control doesn’t, by itself, establish a sale. Keep records that distinguish an internal transfer from an exchange or another disposition.
U.S. Tax Rules and Reporting
U.S. federal rules require taxpayers to keep enough records to support positions on income tax returns. The IRS generally requires U.S. taxpayers to report digital asset sales and other dispositions on Form 8949, Sales and Other Dispositions of Capital Assets.
Tax preparation depends on reconciling activity across exchanges, wallets, and blockchains. Keep transaction records that show transfers between your own wallets and identify any missing data. Choose support that fits your activity and records, whether you need crypto tax reporting, bookkeeping, or return preparation.
U.S. crypto tax services can include transaction reconciliation, cost-basis calculations, tax filing and reporting, and audit and compliance support. Failure-to-file and failure-to-pay penalties can add up to 25% or more of the original tax bill. Tax reporting support can connect transaction records with return preparation.
Federal tax treatment of digital assets as property
U.S. federal tax treatment depends on the nature of each digital asset transaction. A sale, exchange, business receipt, or payment can affect income reporting and capital calculations.
Digital Assets as Property
For U.S. federal tax purposes, cryptocurrency is generally treated as property, not as currency. The IRS issued this classification in 2014, so a digital asset’s value and transaction history matter when it’s sold or exchanged.
The Infrastructure Investment and Jobs Act defines a digital asset as a digital representation of value recorded on a cryptographically secured distributed ledger or similar technology. The definition can include cryptocurrency and other assets recorded on such ledgers. This classification shapes how taxpayers record purchases, sales, transfers, and business receipts.
Custody also matters for accurate records. A wallet or platform may hold assets for you, while a self-hosted wallet records activity under your control. For each transaction, connect the asset and its value to the event that changed its ownership or use.
Gains and Losses on Dispositions
A disposition is an event that ends or changes your ownership of an asset, such as selling or exchanging it. The difference between the asset’s basis and its proceeds generally determines whether the transaction produces a capital gain or loss.
For example, exchanging digital assets for another asset can still create a reportable disposition, even if no U.S. dollars change hands. The Internal Revenue Service (IRS) says U.S. taxpayers generally report digital asset sales and other dispositions on Form 8949, Sales and Other Dispositions of Capital Assets.
An individual may generally use up to $3,000 of excess capital losses to offset other income, according to the Internal Revenue Service (IRS). High-income earners may owe an additional 3.8% net investment income tax on short- and long-term capital gains, according to the Internal Revenue Service (IRS).
Tax Forms and Revenue Recognition
Different forms address dispositions, income, and broker reporting. The Internal Revenue Service (IRS) requires brokers to report digital asset transactions on Form 1099-DA for transactions on or after Jan. 1, 2025. A broker’s form is one record, not a substitute for tracking activity across wallets and platforms.
Business revenue recognition means recording income when the business receives value. For crypto payments, record the asset’s value and the date received; a later sale or exchange is a separate transaction to evaluate. Mining can also create income, while employees and independent contractors report crypto compensation through different tax forms.
Strong accounting connects wallet custody records, transaction details, and tax reporting. To align digital asset records with business reporting, discuss your accounting needs.
How does the IRS treat crypto gifts and charitable donations?
U.S. federal tax treatment depends on whether crypto is bought, exchanged, gifted, donated, or received as a reward. The transaction type and supporting records shape how the activity is reported.
Gifts and charitable donations
U.S. taxpayers who give digital assets as gifts use Form 709, United States Gift (and Generation-Skipping Transfer) Tax Return. For 2025, a person may give up to $19,000 per recipient without filing Form 709. The amount applies per recipient, so records should identify each recipient and the value and date of each transfer.
A charitable donation is different from a personal gift, so keep the documentation separate. Record the recipient organization, asset, transfer date, and value at the time of transfer. These details help distinguish a donation from a sale, exchange, or payment. A blockchain transfer alone doesn’t establish the transfer’s tax character, so retain records showing its purpose and recipient.
Purchases, exchanges, and sales tax
Buying cryptocurrency with U.S. dollars is different from exchanging one digital asset for another. A crypto-to-crypto exchange can be a taxable disposition because the IRS treats cryptocurrency as property. Track the asset given up, its cost basis, and the value received. Even when no cash reaches your bank account, an exchange requires records for both sides of the transaction.
State sales tax is separate from federal income tax. Whether sales tax applies to goods or services purchased with crypto depends on the state and the item or service. Paying with a blockchain asset doesn’t, by itself, determine whether the purchase is subject to sales tax. Keep the purchase receipt with the transaction record.
Mining, staking, and airdrops
Mining and staking rewards can create ordinary income when earned. The value of mined crypto is generally measured at fair market value on the day it is received. For U.S. federal reporting, the Internal Revenue Service (IRS) says ordinary income from digital asset forks, staking, and mining is reported on Form 1040 (Schedule 1), Additional Income and Adjustments to Income.
Centralized platforms and decentralized blockchain protocols may display rewards differently, so preserve both platform statements and wallet transactions. For an airdrop, record when the asset appears, its value, and any later exchange or sale. Keep the receipt separate from a later disposition, since each event may have its own reporting consequences. A clear timeline helps connect rewards, gifts, donations, and purchases to the right records.
Ordinary income from mining, staking, airdrops, and services
U.S. federal tax treatment distinguishes ordinary income from gains or losses on later dispositions. The same crypto asset can create separate tax events when you receive it and later sell it.
Crypto Rewards as Ordinary Income
Ordinary income is value received for activities such as mining, staking, or providing services, rather than profit from selling an investment. It matters because taxpayers may owe income tax when rewards are earned, before converting them into dollars. For U.S. federal returns, the Internal Revenue Service (IRS) says ordinary income from digital asset forks, staking, and mining is reported on Form 1040 (Schedule 1), Additional Income and Adjustments to Income.
For mining, record the reward’s fair market value on the day it arrives, along with the receipt date and wallet details. This value establishes income and can also inform the asset’s basis for a later sale. A platform statement or blockchain record can help document when you received the reward.
U.S. ordinary income tax rates range from 10% to 37%, based on the taxpayer’s income tax bracket. State and local income taxes are separate from federal filing obligations; the applicable jurisdiction and income classification affect whether they apply. Keep federal and state records distinct.
Crypto Income for Services
Crypto income for services is the value of digital assets received as payment for work. It matters because receiving crypto can create taxable income even when the recipient keeps the asset rather than exchanging it. For example, a service provider who receives $50 worth of crypto for computer repair recognizes $50 of ordinary income.
U.S. employees report digital asset wages on Form 1040, while independent contractors report crypto payments on Schedule C (Form 1040). Employers paying wages in crypto should treat its fair market value like other wages, including applicable federal withholding and employment taxes. Contractors should keep invoices and payment records that connect work performed with the crypto received.
Record mining, staking, airdrops, and service payments separately from later sales or swaps. A later disposition may create a capital gain or loss, measured using the asset’s basis and disposition value. This distinction keeps reward income separate from investment proceeds.
Crypto tax software can import platform data and organize transactions, while a tax professional can analyze complex records and prepare filings. Professional tax filing and compliance support can also address amended returns, IRS notices, and back taxes by reviewing prior filings, transaction records, and reported income.
Crypto as payment for goods, services, or wages
Paying or receiving crypto can create more than one U.S. federal tax consequence. The recipient may have income, while the payer may dispose of a property asset. Separate records for each side clarify how the payment affects reporting.
If your business accepts crypto for goods or services, record the transaction date, asset received, and its fair market value at receipt. That value generally establishes the amount received for the sale or service. Keep the invoice with the related wallet or payment-platform record so accounting entries can be traced to the customer transaction.
The payer also needs to account for the crypto used. Because the IRS treats cryptocurrency as property, spending it can count as a disposition. Compare the asset’s basis with its value when used to determine whether the payment produced a capital gain or loss. The product purchase and the crypto disposal are distinct parts of the same transaction.
Wages paid in digital assets follow U.S. federal employment-tax rules. Employers should treat the crypto’s fair market value similarly to other wages and subject it to Social Security tax, Medicare tax, FUTA taxes, and federal income tax withholding. The asset’s value when paid is therefore relevant to payroll records and the employee’s income reporting.
Employees report digital asset wages on Form 1040. Independent contractors report crypto payments for services on Schedule C (Form 1040). For either recipient, the payment record should connect the work or payroll period with the asset amount and value received. The contractor’s later sale or exchange is a separate event, using the receipt value as a reference point for basis.
Broker reporting and payment records serve different purposes. A Form 1099-DA can report certain digital asset transactions, but a business still needs records showing why it received or transferred crypto. Keep invoices, payroll entries, platform statements, and wallet transaction identifiers aligned. This supports income tax reporting and helps explain the payment’s business purpose.
For Web3 teams, payment controls should define how staff record crypto receipts, customer refunds, payroll, and later asset conversions. Reconcile accounting entries against blockchain records and platform statements, then separate wage income from customer revenue and investment dispositions. Clear categories reduce confusion when a single wallet contains assets from several business activities.
If your business accepts crypto or pays contributors in digital assets, discuss your crypto payment accounting needs.
Block3 Finance: Audits and Compliance
Block3 Finance helps individuals and Web3 teams bring crypto activity into clear, supportable tax records. When transactions span wallets, platforms, payments, and rewards, its Tax Filing and Reporting and Audits and Compliance services can help organize the records and address reporting obligations.
Turn to this support when preparing a return, reconciling business activity, or responding to an audit concern. Monthly Accounting can connect digital asset transactions with ongoing financial records, while a Crypto Tax Accountant can help classify income and dispositions for tax reporting. The focus is practical: align transaction histories, supporting documents, and return positions.
If you need help bringing your crypto tax records and reporting into order, contact Block3 Finance to discuss your needs.
Build a stronger crypto tax process
For U.S. businesses and Web3 teams, tax readiness works best as part of operational design, not a reconstruction exercise at filing time. Assign responsibility for transaction data, establish how records move from platforms into accounting, and define how unusual activity is escalated for review. These controls help teams make informed decisions as their operations evolve.
A consistent process also supports continuity when teams change systems, add new workflows, or expand how they use digital assets. Crypto tax compliance services can help connect transaction records with accounting and reporting needs, giving decision-makers a clearer foundation for their next steps. The aim is practical: make sound recordkeeping part of how the organization operates.
Block3 Finance can help you shape that process around your crypto activity and reporting needs. Contact Block3 Finance about your crypto taxes and take the next step with greater clarity.
Frequently Asked Questions
Are crypto losses tax deductible?
Yes. Under U.S. federal rules, realized crypto losses can offset capital gains, and individuals may use excess capital losses against other income within applicable limits. A drop in an asset’s market value alone doesn’t establish a deductible loss; you must dispose of the asset. Keep records of the disposal, basis, proceeds, and related fees to document the loss.
How Should Investors Prepare?
Before calculating gains, losses, or income, organize your transaction records. Gather exchange statements, wallet histories, purchase records, and documents for rewards or crypto payments. Match transfers between wallets you control so they aren’t mistaken for sales or exchanges. Then group activity by type, such as purchases, dispositions, income, and gifts. This gives your tax preparer a traceable record of what happened and when.
How do cryptocurrency transaction fees play into it?
Transaction fees can affect the proceeds used to calculate a crypto sale’s gain or loss. For example, if an asset sells for $17,000 and the transaction has $500 in fees, the net proceeds are $16,500. Keep the fee amount with the sale record rather than treating it as an unrelated expense. This helps reconcile exchange statements with the proceeds reported for the disposition.
Taxable Events: When Does Crypto Trigger a Tax Bill?
Under U.S. federal rules, selling crypto, exchanging it for another digital asset, or spending it can trigger a taxable disposition. Receiving crypto for services, mining, or staking can create income instead. For example, swapping one token for another may require a gain-or-loss calculation even without a cash withdrawal. Document transfers between wallets you control clearly so they aren’t mistaken for sales.
What Is Crypto Tax Liability and What Do You Owe the IRS?
Crypto tax liability is the federal tax resulting from reportable crypto income and dispositions on your return. The amount depends on factors such as income, gains, losses, holding period, and applicable tax rates. Crypto activity is reported on Form 1040, not on a separate crypto return. To estimate what you owe, combine crypto records with the rest of your tax information, rather than treating each wallet as a separate return.
What Is Form 1099-DA?
Form 1099-DA is a broker information return for reporting digital asset transactions. The Internal Revenue Service (IRS) requires brokers to report digital asset transactions on Form 1099-DA for transactions on or after Jan. 1, 2025. Treat a received form as one source record, then reconcile its information with your own exchange and wallet history. A broker’s report may not show every transaction across all platforms or wallets.
How are crypto sales, swaps, staking rewards, mining, and airdrops taxed in the U.S.?
In the U.S., sales and swaps generally require a capital gain-or-loss calculation, and spending crypto can also count as a disposition. Mining and staking rewards can be ordinary income when received. Airdrops and forks require clear records to identify receipt and later activity. Keep the receipt separate from a later sale or exchange, since each event can have different tax treatment and reporting details.
What records and documents do crypto tax services need to prepare a return?
Useful records include exchange statements, wallet addresses, transaction histories, acquisition details, sale or exchange proceeds, and fee records. Include dates and transaction identifiers where available, along with documents for mining or staking rewards, airdrops, crypto wages, and service payments. Business filers should also provide relevant invoices or payroll records. These materials help reconcile on-chain activity with accounting records and identify gaps before preparing tax forms.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
Are crypto losses tax deductible?
Yes. Under U.S. federal rules, realized crypto losses can offset capital gains, and individuals may use excess capital losses against other income within applicable limits. A drop in an asset’s market value alone doesn’t establish a deductible loss; you must dispose of the asset. Keep records of the disposal, basis, proceeds, and related fees to document the loss.
How Should Investors Prepare?
Before calculating gains, losses, or income, organize your transaction records. Gather exchange statements, wallet histories, purchase records, and documents for rewards or crypto payments. Match transfers between wallets you control so they aren’t mistaken for sales or exchanges. Then group activity by type, such as purchases, dispositions, income, and gifts. This gives your tax preparer a traceable record of what happened and when.
How do cryptocurrency transaction fees play into it?
Transaction fees can affect the proceeds used to calculate a crypto sale’s gain or loss. For example, if an asset sells for $17,000 and the transaction has $500 in fees, the net proceeds are $16,500. Keep the fee amount with the sale record rather than treating it as an unrelated expense. This helps reconcile exchange statements with the proceeds reported for the disposition.
Taxable Events: When Does Crypto Trigger a Tax Bill?
Under U.S. federal rules, selling crypto, exchanging it for another digital asset, or spending it can trigger a taxable disposition. Receiving crypto for services, mining, or staking can create income instead. For example, swapping one token for another may require a gain-or-loss calculation even without a cash withdrawal. Document transfers between wallets you control clearly so they aren’t mistaken for sales.
What Is Crypto Tax Liability and What Do You Owe the IRS?
Crypto tax liability is the federal tax resulting from reportable crypto income and dispositions on your return. The amount depends on factors such as income, gains, losses, holding period, and applicable tax rates. Crypto activity is reported on Form 1040, not on a separate crypto return. To estimate what you owe, combine crypto records with the rest of your tax information, rather than treating each wallet as a separate return.
What Is Form 1099-DA?
Form 1099-DA is a broker information return for reporting digital asset transactions. The Internal Revenue Service (IRS) requires brokers to report digital asset transactions on Form 1099-DA for transactions on or after Jan. 1, 2025. Treat a received form as one source record, then reconcile its information with your own exchange and wallet history. A broker’s report may not show every transaction across all platforms or wallets.
How are crypto sales, swaps, staking rewards, mining, and airdrops taxed in the U.S.?
In the U.S., sales and swaps generally require a capital gain-or-loss calculation, and spending crypto can also count as a disposition. Mining and staking rewards can be ordinary income when received. Airdrops and forks require clear records to identify receipt and later activity. Keep the receipt separate from a later sale or exchange, since each event can have different tax treatment and reporting details.
What records and documents do crypto tax services need to prepare a return?
Useful records include exchange statements, wallet addresses, transaction histories, acquisition details, sale or exchange proceeds, and fee records. Include dates and transaction identifiers where available, along with documents for mining or staking rewards, airdrops, crypto wages, and service payments. Business filers should also provide relevant invoices or payroll records. These materials help reconcile on-chain activity with accounting records and identify gaps before preparing tax forms.