Relying solely on broker-reported tax forms is one of the fastest ways to invite unwanted scrutiny from the IRS. If your trading activity spans decentralized wallets and centralized exchanges, calculating crypto capital gains often feels like trying to assemble a puzzle with missing pieces. You shouldn't have to guess whether your crypto-to-crypto swaps will trigger an unexpected audit letter.
Unreported transfers between your own accounts frequently distort your cost basis, which is the original acquisition value of an asset used to measure taxable profit. In this guide, you'll learn the exact IRS framework for tracking your cost basis and calculating crypto capital gains with audit-ready accuracy.
We will explore the 2026 capital gains tax brackets, evaluate cost-basis accounting methodologies like First-In, First-Out (FIFO) versus Specific Identification, and outline how to handle Form 1099-DA reports. You'll gain a clear roadmap to normalize complex on-chain records and submit a defensible tax return.
Key Takeaways
- Understand how IRS property rules treat crypto-to-crypto swaps, spending, and sales as distinct taxable dispositions.
- Learn to establish fair market value in U.S. Dollars at the exact acquisition timestamp, including allowable network fees in your cost basis.
- Compare FIFO and Specific Identification to determine the most tax-efficient inventory methodology when calculating crypto capital gains.
- Execute a standardized five-stage workflow to normalize trade timestamps across decentralized wallets and centralized exchanges.
- Build a defensible paper trail on Form 8949 to reconcile broker-reported data and safeguard your return against IRS discrepancies.
Understanding IRS Taxable Events and Crypto Dispositions
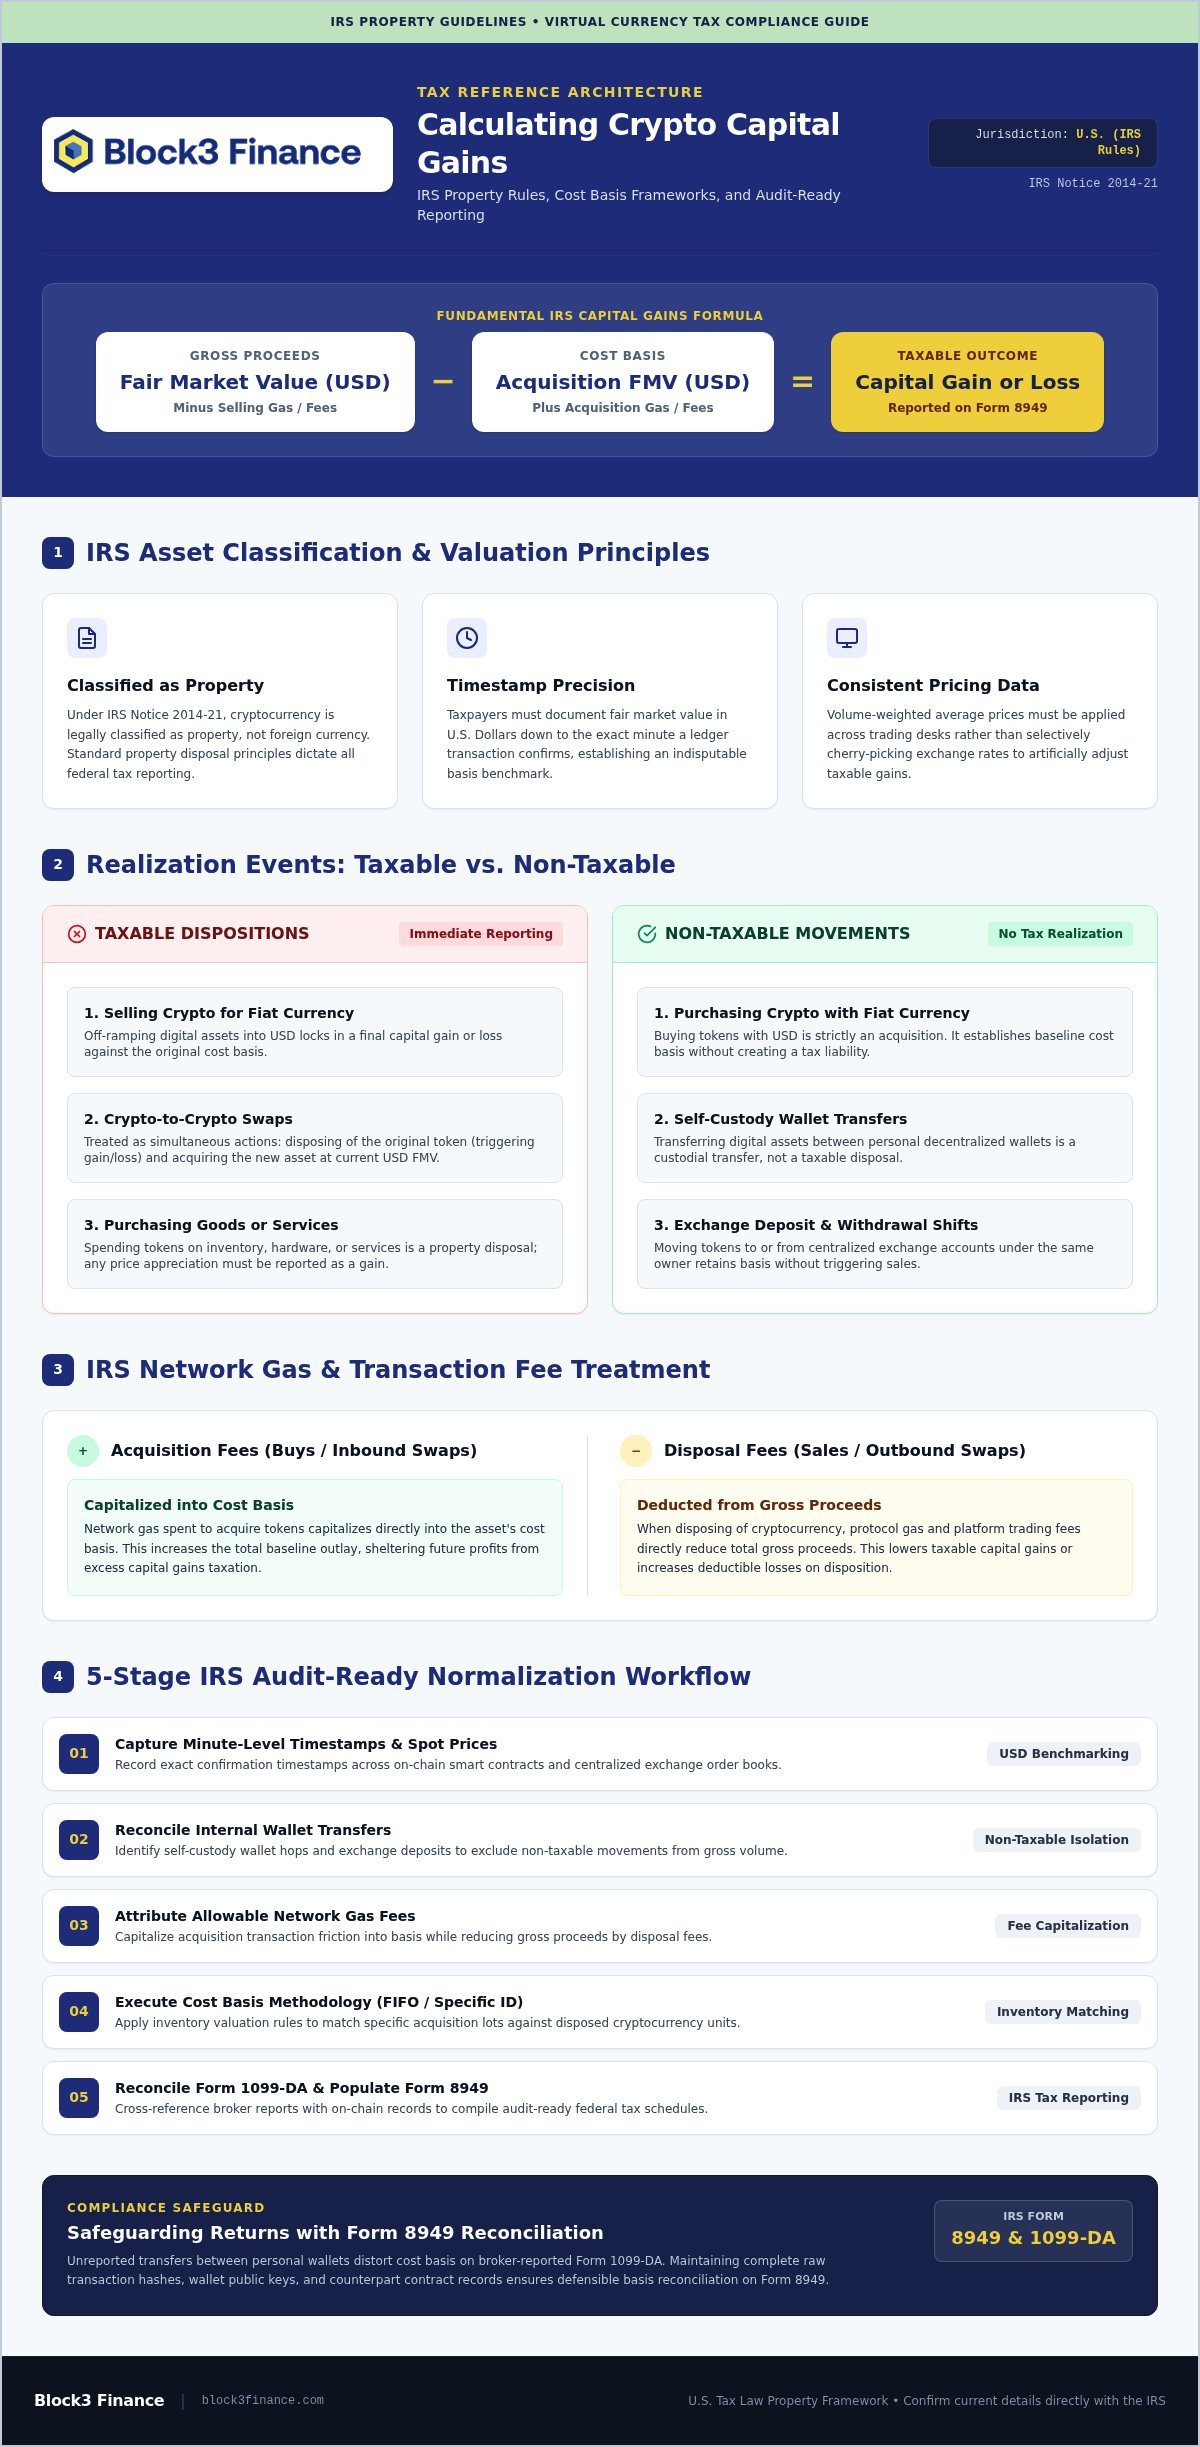
Every transaction involving digital assets begins with classification. Under IRS Notice 2014-21, U.S. tax law classifies crypto as property rather than foreign currency. This foundational rule means that standard property principles dictate how you report every disposal to the federal government.
When calculating crypto capital gains, you must measure the exact spread between your proceeds and your cost basis. If the gross value of the asset you receive exceeds your acquisition cost, you trigger a taxable gain. Conversely, if the fair market value drops below that benchmark, you incur a capital loss.
What Qualifies as a Taxable Realization Event?
A realization event occurs whenever an asset leaves your possession in exchange for economic value. Under IRS rules, several primary transactions trigger this immediate reporting obligation:
- Selling crypto for fiat: Off-ramping tokens into U.S. Dollars constitutes a final sale, locking in a reportable gain or loss.
- Crypto-to-crypto swaps: Exchanging one token for another on a centralized platform or a decentralized liquidity pool is treated as two simultaneous actions. You must calculate capital gains on the disposed token using its fair market value in USD at that second, before establishing the newly acquired asset's basis.
- Purchasing goods or services: Spending cryptocurrency directly to buy hardware, merchant inventory, or digital services represents a property disposal, requiring you to report any value appreciation as a capital gain.
Non-Taxable Blockchain Transfers and Wallet Shifts
Not every on-chain movement generates a tax obligation under IRS rules. Many taxpayers mistakenly report routine operational transfers, inflating their gross volume and distorting their tax liability.
Purchasing cryptocurrency with fiat currency is strictly an acquisition, which creates your baseline cost basis without creating a taxable event. Similarly, transferring digital assets between your own self-custody wallets or moving them to exchange deposit addresses is completely non-taxable.
These movements represent simple custodial changes rather than disposals. Maintaining clear records of internal wallet transfers ensures you avoid misclassifying non-taxable movements as sales when calculating crypto capital gains.
Determining Your Cost Basis Under IRS Guidelines
Establishing an airtight cost basis forms the bedrock of accurate tax reporting. Per official IRS guidelines on virtual currency, your basis represents the complete capital outlay required to secure an asset. This figure includes the acquisition price alongside allowable transaction costs.
Documenting these numbers prevents double taxation when you eventually dispose of your holdings. When calculating crypto capital gains, a missing or zeroed basis drastically inflates your taxable profit, creating an artificial tax liability that damages your portfolio performance.
Tracking Fair Market Value at Acquisition
Under IRS regulations, taxpayers must capture fair market value in U.S. Dollars at the exact moment a transaction confirms. Automated smart contract executions and decentralized exchange swaps require meticulous records:
- Timestamp precision: Record spot prices down to the minute a transaction completes on the ledger.
- Reliable pricing sources: Apply consistent volume-weighted average prices across all centralized trading desks rather than cherry-picking favorable exchange rates.
- Defensible documentation: Preserve raw transaction hashes, wallet public keys, and counterpart contracts to substantiate your numbers during an examination.
Accounting for Gas Fees and Network Transaction Costs
On-chain activity introduces complex friction through protocol fees. Network gas spent to acquire an asset, such as swapping through an automated market maker, capitalizes directly into that asset's cost basis. This adjustment increases your baseline cost and shelters future gains.
Disposal fees behave differently under federal rules. When you sell or swap tokens, the associated gas and platform trading fees reduce your total gross proceeds. Tracking these distinctions across complex DeFi interactions requires granular reconciliation; if you manage high-volume smart contract activities, you can consult a dedicated crypto tax team to review your transaction ledgers.
Separating capitalized transaction costs from ordinary network usage safeguards your calculations. With verified cost basis records in place, you can move toward selecting the proper accounting method to calculate crypto capital gains with audit-ready accuracy.
Selecting an Accounting Method: FIFO, LIFO, or Specific ID
Your choice of accounting methodology directly impacts your tax bill. Under current IRS guidelines on virtual currency, the federal government treats First-In, First-Out (FIFO) as your default posture unless you deliberately establish an alternative. That choice controls whether your profits qualify as short-term or long-term holdings.
Switching methods mid-year without clean, contemporaneous records creates immediate exposure during an agency audit. When calculating crypto capital gains, disciplined lot selection turns passive compliance into an offensive tool for preserving liquidity.
First-In, First-Out (FIFO) Default Standards
Under basic FIFO rules, the oldest tokens you acquired are deemed the first ones sold. This framework simplifies bookkeeping across high-frequency trades, but it often works against long-term investors.
Because early blockchain assets were typically acquired at much lower valuations, FIFO often accelerates taxable profits into your current return. This sequence converts legacy low-basis positions into heavy capital gains when token prices appreciate over several market cycles.
Specific Identification and Universal Wallet Tracking
Specific Identification (Specific ID) gives you total command over your tax exposure by allowing you to choose exactly which lots leave your inventory. Taxpayers commonly use Highest-In, First-Out (HIFO), which is a lot-selection strategy permitted under Specific ID rules that prioritizes high-basis purchases to minimize current-year liabilities.
To use this approach defensibly, the IRS requires strict, verifiable proof before an execution occurs:
- Acquisition timestamps: Log the exact date, minute, and second each token entered your portfolio.
- Historical valuation: Record the precise USD value and associated transaction fees when the lot was created.
- Wallet identifiers: Isolate lots by specific hardware addresses or exchange accounts, since universal cross-wallet pooling is restricted under recent IRS rules.
Failing to supply these granular records will cause revenue agents to default your return back to FIFO. Leveraging professional tax filing and reporting services ensures your accounting method withstands strict regulatory scrutiny while calculating crypto capital gains across all self-custody and institutional accounts.
Step-by-Step Guide to Calculating Crypto Capital Gains
Executing a defensible tax calculation requires a structured workflow rather than haphazard spreadsheet entries. Without a systematic approach, fragmented wallet histories quickly lead to reporting errors. Following a defined five-stage process brings complete clarity to calculating crypto capital gains under federal rules:
- Aggregate raw data: Export ledgers from every exchange and self-custody wallet.
- Normalize entries: Convert all transaction timestamps into a uniform time standard like Coordinated Universal Time (UTC).
- Match internal transfers: Pair outgoing and incoming wallet transfers to prevent non-taxable movements from registering as sales.
- Apply accounting methodology: Match disposals against corresponding acquisition lots using FIFO or Specific ID.
- Net the results: Reconcile total gains against losses across holding periods.
Aggregating Multi-Wallet and Exchange Transaction Data
Disparate platforms export data in conflicting formats. Centralized exchanges provide CSV exports and read-only API logs, while on-chain activities require querying public block explorers. You must translate diverse columns into a unified ledger that clearly captures asset amounts, USD valuations, execution fees, and transaction hashes.
Failing to reconcile self-transfers across accounts creates artificial taxable sales, which distorts your final figures. Traders handling fragmented books across multiple protocols can explore our comprehensive guide to cryptocurrency tax filing for institutional reporting standards, or contact our specialized team to resolve multi-wallet transaction trails.
Separating Short-Term from Long-Term Capital Gains
IRS tax provisions separate capital gains into two distinct buckets based strictly on holding duration. Assets owned for one year or less trigger short-term capital gains, which are taxed at ordinary income rates ranging from 10% to 37% for the 2026 tax year. Tokens held for more than 365 days qualify for preferential long-term rates of 0%, 15%, or 20%.
Once you categorize each trade, IRS rules require you to net short-term gains against short-term losses first. You then repeat that exact netting process for long-term positions before combining the outcomes. This structured sequence ensures your final tax submission reflects your genuine economic position while calculating crypto capital gains.
Building an Audit-Ready Crypto Tax Record for the IRS
Federal tax scrutiny has shifted from voluntary reporting toward automated compliance checks. The IRS relies on advanced data-matching routines to compare taxpayer filings against broker forms like Form 1099-DA, which reports gross proceeds and cost basis for covered digital assets. An unverified mismatch between your return and broker-submitted data often generates an automated inquiry notice.
Submitting an audit-ready filing requires substantiating every line item on IRS Form 8949 (Sales and Other Dispositions of Capital Assets). You must list the asset description, exact acquisition date, disposal date, proceeds, and cost basis for each individual trade. Preserving raw blockchain data protects your return during formal information requests when calculating crypto capital gains.
Common Calculation Pitfalls in DeFi and Margin Trades
Complex on-chain mechanics frequently introduce hidden realization events that standard retail tax apps misclassify. These specialized transactions require careful review to prevent substantial reporting mistakes:
- Liquidity pool deposits: Minting liquidity provider tokens by depositing paired assets can be viewed by the IRS as a taxable exchange of property.
- Margin liquidations: When an automated protocol liquidates collateral to cover a debt, that forced disposal constitutes a property disposition requiring capital gain or loss recognition.
- Cross-chain wrapping: Depositing assets into bridge contracts often logs as a sale rather than a non-taxable wrap if the original contract fails to preserve your cost basis.
Partnering with a Specialized Crypto Tax Firm
Automated retail calculators struggle to reconcile high-volume decentralized trading and complex staking distributions. High-net-worth operators, DAOs, and active funds require institutional-grade verification rather than unvetted CSV imports. Engaging a specialized accounting team ensures your on-chain activity translates into defensible tax documentation.
Adopting proactive monthly crypto accounting solutions eliminates the annual panic of chasing missing basis values across deprecated smart contracts. Ranked as a top crypto accounting provider by Bitcoin.com, the specialists at Block3 Finance leverage over 13 years of blockchain accounting expertise to structure clean, audit-ready records. Having served more than 980 clients, our firm ensures your calculations remain defensible under IRS scrutiny while calculating crypto capital gains.
Take Control of Your On-Chain Tax Compliance
Gaining total clarity over your digital asset obligations requires rigorous basis tracking, deliberate lot selection, and full reconciliation of every transfer across chains. When calculating crypto capital gains under IRS rules, disciplined bookkeeping transforms complex decentralized protocols and exchange histories into defensible records. Establishing this audit-ready posture shields your portfolio from automated compliance notices.
You don't need to tackle fragmented trading books and multi-wallet histories on your own. Recognized as a top crypto accounting provider by Bitcoin.com, Block3 Finance brings over 13 years of specialized digital asset accounting expertise. Having successfully guided more than 980 clients through high-stakes compliance, our team resolves transaction friction before it triggers federal inquiries.
Partner with Block3 Finance for audit-ready crypto tax filing and secure complete peace of mind this tax season. Taking control of your compliance today ensures your digital assets remain an engine for growth rather than an operational burden.
Frequently Asked Questions
What is the formula used for calculating crypto capital gains under IRS rules?
The standard formula is gross proceeds minus adjusted cost basis. Gross proceeds represent the fair market value in U.S. Dollars at disposal, minus allowable selling fees. Your cost basis includes the initial acquisition price plus capitalized network gas expenses. If the result is positive, you have a capital gain; if negative, you incur a capital loss.
How does the IRS determine whether crypto capital gains are short-term or long-term?
Holding duration dictates the tax classification under federal guidelines. The IRS starts counting your holding period the day after you acquire the digital asset. Holding cryptocurrency for one year or less results in short-term gains taxed at ordinary income rates. Holding an asset for more than 365 days qualifies your profits for preferential long-term capital gains tax rates.
Do I owe capital gains taxes if I transfer crypto between my own personal wallets?
No, transferring digital assets between your own self-custody wallets or exchange deposit addresses is non-taxable under IRS rules. These events represent shifts in custody rather than economic realizations or disposals. You must track and document the original acquisition date and cost basis so internal transfers don't mistakenly register as taxable sales.
Can I deduct cryptocurrency capital losses against regular income on my US tax return?
Yes, net capital losses can offset ordinary income under specific federal limits. After offsetting all capital gains, U.S. taxpayers can deduct up to $3,000 of net capital losses against ordinary income per year, or $1,500 if married filing separately. Any unused excess losses carry forward indefinitely to offset taxable income in future years.
Which accounting method should I use: FIFO, LIFO, or Specific Identification?
The optimal method depends on your records and broader tax goals. The IRS mandates First-In, First-Out (FIFO) as the default method if detailed lot tracking is missing. If you maintain contemporaneous records of transaction times, hashes, and valuations, Specific Identification (or HIFO) lets you select higher-basis lots to strategically minimize gains when calculating crypto capital gains.
What IRS tax forms are required to report cryptocurrency capital gains and losses?
Dispositions must be recorded on Form 8949 (Sales and Other Dispositions of Capital Assets). You report individual sales, trades, and payments with their acquisition dates, disposal dates, proceeds, and cost basis. The summarized totals from Form 8949 are then transferred onto Schedule D of Form 1040 to finalize your federal return.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
What Qualifies as a Taxable Realization Event?
A realization event occurs whenever an asset leaves your possession in exchange for economic value. Under IRS rules, several primary transactions trigger this immediate reporting obligation:
What is the formula used for calculating crypto capital gains under IRS rules?
The standard formula is gross proceeds minus adjusted cost basis. Gross proceeds represent the fair market value in U.S. Dollars at disposal, minus allowable selling fees. Your cost basis includes the initial acquisition price plus capitalized network gas expenses. If the result is positive, you have a capital gain; if negative, you incur a capital loss.
How does the IRS determine whether crypto capital gains are short-term or long-term?
Holding duration dictates the tax classification under federal guidelines. The IRS starts counting your holding period the day after you acquire the digital asset. Holding cryptocurrency for one year or less results in short-term gains taxed at ordinary income rates. Holding an asset for more than 365 days qualifies your profits for preferential long-term capital gains tax rates.
Do I owe capital gains taxes if I transfer crypto between my own personal wallets?
No, transferring digital assets between your own self-custody wallets or exchange deposit addresses is non-taxable under IRS rules. These events represent shifts in custody rather than economic realizations or disposals. You must track and document the original acquisition date and cost basis so internal transfers don't mistakenly register as taxable sales.
Can I deduct cryptocurrency capital losses against regular income on my US tax return?
Yes, net capital losses can offset ordinary income under specific federal limits. After offsetting all capital gains, U.S. taxpayers can deduct up to $3,000 of net capital losses against ordinary income per year, or $1,500 if married filing separately. Any unused excess losses carry forward indefinitely to offset taxable income in future years.
Which accounting method should I use: FIFO, LIFO, or Specific Identification?
The optimal method depends on your records and broader tax goals. The IRS mandates First-In, First-Out (FIFO) as the default method if detailed lot tracking is missing. If you maintain contemporaneous records of transaction times, hashes, and valuations, Specific Identification (or HIFO) lets you select higher-basis lots to strategically minimize gains when calculating crypto capital gains.
What IRS tax forms are required to report cryptocurrency capital gains and losses?
Dispositions must be recorded on Form 8949 (Sales and Other Dispositions of Capital Assets). You report individual sales, trades, and payments with their acquisition dates, disposal dates, proceeds, and cost basis. The summarized totals from Form 8949 are then transferred onto Schedule D of Form 1040 to finalize your federal return.